VLSI Korea
Market Bulletin: Packaging Revenue Rises 51% — ASE Reaches US$4.74 Billion as the Back End Scales
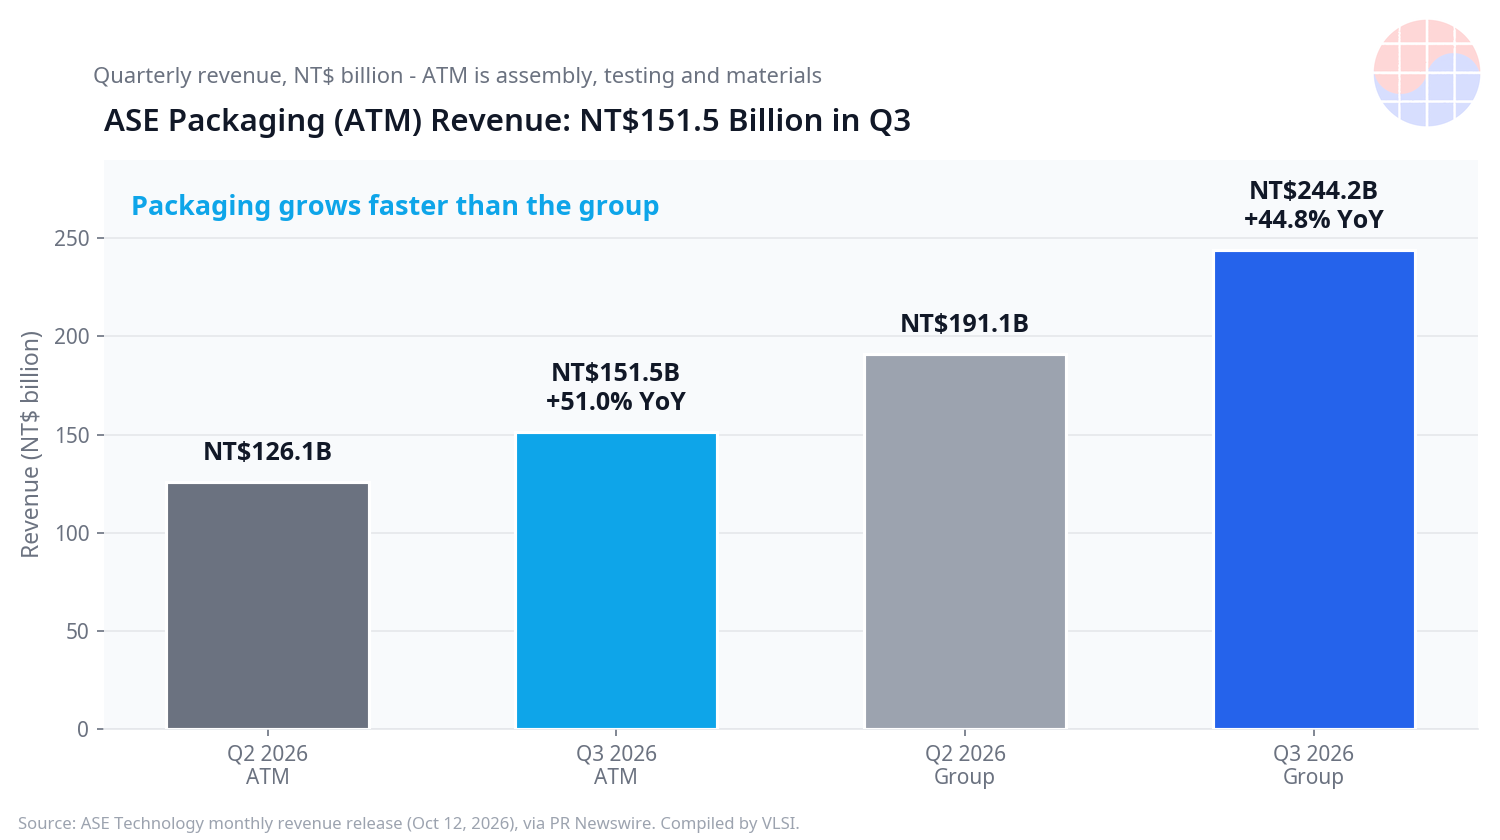
ASE's packaging and test (ATM) revenue rose 51.0% year over year in Q3 2026 to US$4.74 billion, outpacing group growth of 44.8%. ASE lifted 2026 capex to US$10.5 billion and Amkor guided Q3 sales higher. The back end is scaling with the front end.


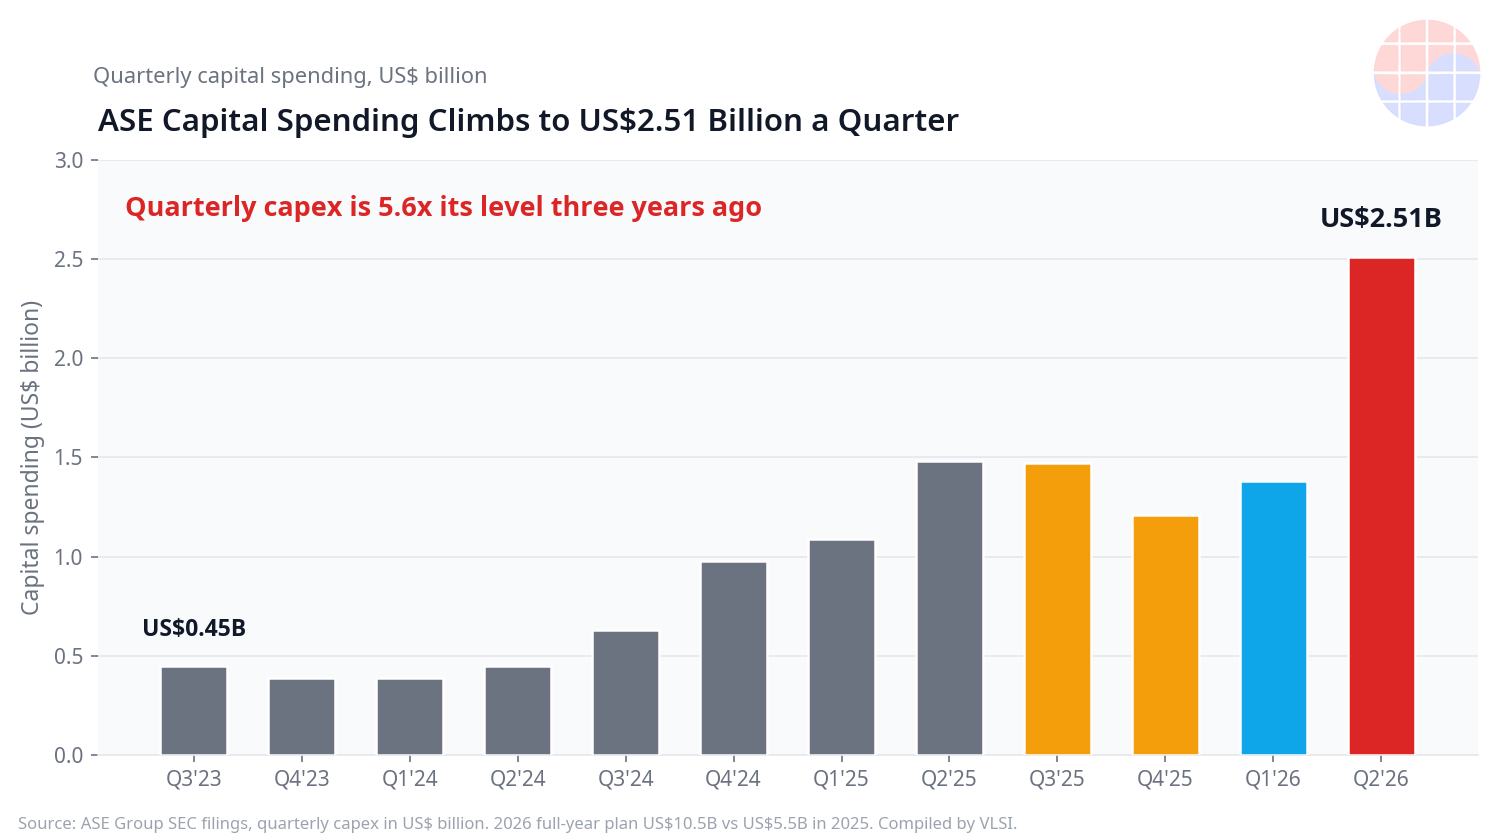
The bottleneck everyone watches is the wafer fab. The numbers say the back end is scaling just as fast. ASE Technology reported third-quarter 2026 assembly, testing and materials (ATM) revenue of NT$151.49 billion (US$4.74 billion), up 20.1% quarter over quarter and 51.0% year over year in Taiwan dollars — 40.6% in US dollars — while group revenue rose 44.8% to NT$244.16 billion (US$7.64 billion) (ASE Technology monthly revenue, October 12, 2026). Packaging is no longer the cheap afterthought after fabrication: ASE is running its leading-edge advanced packaging business above a US$3.5 billion 2026 target and has lifted full-year capex to US$10.5 billion, almost double the US$5.5 billion spent in 2025.
Key Highlights
- ATM +51.0%: ASE's ATM revenue reached NT$151.49 billion (US$4.74 billion) in Q3 2026, up 51.0% year over year in Taiwan dollars and 40.6% in US dollars. It was about 62% of group revenue, and roughly two-thirds of the group's year-over-year revenue increase came from ATM (ASE monthly revenue analysis, October 12, 2026).
- September confirms the run rate: September ATM revenue was NT$52.67 billion (US$1.66 billion), up 50.5% year over year, while group September revenue was NT$88.13 billion (US$2.78 billion), up 45.5% (ASE Technology, October 12, 2026).
- LEAP runs ahead of plan: ASE's LEAP leading-edge advanced packaging revenue is running above a US$3.5 billion target for 2026 that had already been raised from more than US$2.6 billion. Full-year 2026 capex is now planned at US$10.5 billion versus US$5.5 billion in 2025, across 13 greenfield and 8 brownfield projects (ASE capex and LEAP update, October 2026).
- Amkor's record quarter: Amkor posted record Q2 2026 revenue of US$1.90 billion, up 26% year over year, with gross margin expanding to 16.8% from 12% and net income rising to US$174 million from US$54 million. Advanced products generated US$1.56 billion. Q3 guidance is US$1.95-2.05 billion in sales at 18.5-19.5% gross margin, with full-year capex of US$2.5-3.0 billion (Amkor Q2 2026 results via Zacks, 2026).
- Substrates get a US$3.14 billion vote: Samsung Electro-Mechanics will invest 4.27 trillion won (US$3.14 billion) to expand FC-BGA substrate capacity at Sejong — the largest single-product capex in its history — from September 2026 to May 2028, with mass production from September 2028 (Korea Times, September 28, 2026).
Market Update
The structure of the growth matters more than the headline. ATM grew faster than the group in both Taiwan-dollar and US-dollar terms, and its gross margin reached 27.3% in Q2 2026 against a group gross margin of 21.0% — packaging mix, not just volume, is lifting profitability. Quarterly capex tells the same story in cash: ASE spent US$2.51 billion in Q2 2026 alone, 5.6 times the US$0.45 billion of Q3 2023. Capacity is being added in blocks — 13 greenfield and 8 brownfield projects meant to carry supply through 2028 and into 2029 — which is why monthly ATM growth can pause (September was +2.7% month over month) even while the year-over-year rate stays above 50%.
| A year ago / earlier plan | Now (reported or planned) | |
|---|---|---|
| ASE ATM revenue (Q3) | NT$100.3 billion implied (Q3 2025) | NT$151.49 billion (US$4.74 billion), +51.0% YoY in NT$ |
| ASE group revenue (Q3) | NT$168.6 billion implied (Q3 2025) | NT$244.16 billion (US$7.64 billion), +44.8% YoY in NT$ |
| ASE 2026 capex plan | US$5.5 billion spent in 2025 | US$10.5 billion planned for 2026 |
| ASE LEAP advanced packaging | Target above US$2.6 billion | Running above US$3.5 billion target for 2026 |
| Amkor revenue / margin | US$1.51 billion, 12% GM (Q2 2025) | Record US$1.90 billion, 16.8% GM (Q2 2026) |
| Amkor Arizona campus | Phase 1: 33,000 sqm cleanroom | Phase 2 adds 60,000 sqm; total plan about US$12 billion |
ASE figures from the company's unaudited monthly revenue release (October 12, 2026); year-ago quarterly values are implied by the reported growth rates. LEAP and capex plan from ASE disclosures in October 2026. Amkor figures from Q2 2026 results (July 2026). Capex plans and guidance are not reported results.
Amkor shows this is an industry pattern, not one company's quarter. Its Computing revenue hit a record in Q2 2026 on data-center demand, a new data-center CPU program on high-density fan-out began ramping, and management expects Computing revenue to rise nearly 30% sequentially in Q3. Utilization has climbed from the 50s into the 70s, and its Arizona campus — where customer commitments already surpassed the 33,000 square meters planned for Phase 1 — is expanding by another 60,000 square meters in Phase 2, taking the total planned investment to about US$12 billion. One layer down, the substrate is being funded like a strategic asset: Samsung Electro-Mechanics' US$3.14 billion FC-BGA expansion in Sejong is explicitly aimed at AI server demand secured through long-term agreements.
VLSI's View
Packaging is now on the critical path, not after it. An AI accelerator is not a finished product when the wafer leaves the fab. It still needs an interposer or advanced substrate, HBM stacks placed and bonded, and final test — and each of those steps is capacity that must be built years ahead. ASE's ATM segment growing 51% while TSMC's wafer revenue grows on 2nm mix is the same wave measured at two different stations: front end and back end are scaling together, and either one can gate server shipments.
The Korea angle runs through substrates and memory packaging. Samsung Electro-Mechanics committing US$3.14 billion to FC-BGA in Sejong — its largest single-product investment ever, running to May 2028 — is Korea buying a position in the layer between the chip and the board. The same logic applies to HBM: every stack is an advanced packaging product before it is a memory product. Korean suppliers that treat packaging and substrates as commodity back-end work will miss where the margin is moving — ASE's ATM gross margin of 27.3% already sits well above its group average.
Execution, not demand, is now the stated constraint. ASE itself frames the limit as how fast equipment can be installed across 21 projects. That is a familiar shape to anyone in chip implementation: when utilization rises and the schedule is set by tool delivery and cleanroom readiness, lead times stretch in steps, not smoothly. Buyers should read monthly ATM plateaus as capacity blocks coming online, not as demand signals.
Chase's Take: In physical design we learned this the hard way: a design is not done when synthesis finishes — it is done when it closes timing, passes DRC and tapes out. AI silicon has the same definition problem. A wafer is inventory, not compute, until packaging and test turn it into a shippable accelerator. The market still prices the fab step as the story and the back end as a footnote; ASE adding US$5 billion of capex in one year says the footnote is becoming a chapter.
Outlook
- ASE Q3 earnings on October 29: margins and any LEAP revenue disclosure will test whether the 51% growth is converting into profit at the guided rate.
- Q4 monthly revenue: whether ATM reaccelerates from September's +2.7% month-over-month as new capacity blocks come online.
- Amkor Q3 results: sales guided at US$1.95-2.05 billion with gross margin of 18.5-19.5% — a direct read on advanced packaging pricing power.
- 2027 LEAP target: ASE targets roughly doubling leading-edge advanced packaging revenue in 2027; watch whether the US$10.5 billion capex plan holds or rises again.
FAQ
How fast is ASE's packaging business growing? ASE's assembly, testing and materials (ATM) revenue was NT$151.49 billion (US$4.74 billion) in Q3 2026, up 51.0% year over year in Taiwan dollars and 40.6% in US dollars, outpacing group revenue growth of 44.8% (ASE Technology, October 12, 2026).
What is LEAP and how big is it? LEAP is ASE's leading-edge advanced packaging business for AI and high-performance computing chips. Its 2026 revenue is running above a US$3.5 billion target, raised from more than US$2.6 billion, and ASE targets roughly doubling it in 2027 (ASE, October 2026).
How much are packaging companies investing? ASE plans US$10.5 billion of capex in 2026, almost double the US$5.5 billion of 2025. Amkor expects US$2.5-3.0 billion in 2026 and about US$12 billion in total for its Arizona campus. Samsung Electro-Mechanics is investing US$3.14 billion in FC-BGA substrates (company disclosures, 2026).
Why does advanced packaging matter for AI servers? AI accelerators combine a large processor die with HBM memory stacks on an interposer or advanced substrate. Until packaging and final test are complete, a fabricated wafer cannot ship as a working accelerator, so back-end capacity directly gates AI server supply.
📩 Subscribe to VLSI Korea
Get our daily semiconductor deep-dives delivered to your inbox first. Free to subscribe.