 VLSI Korea
Synopsys stock jumps 12.78%: Amazon, OpenAI and the earnings reset
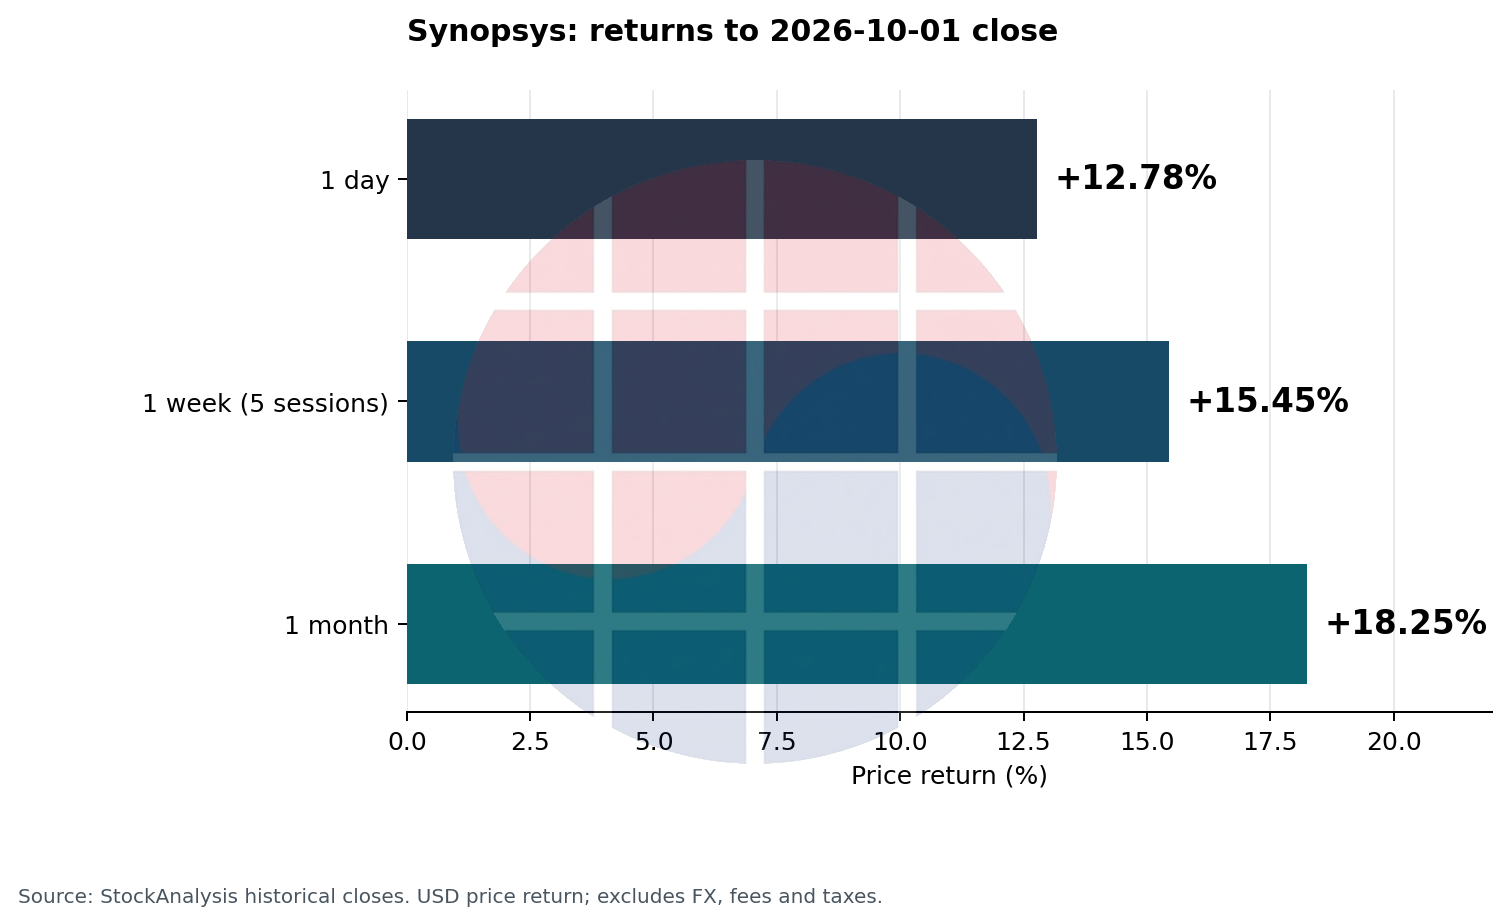
SNPS rose 12.78% in a day, 15.45% in a week and 18.25% in a month. The Amazon and OpenAI deals, FY2027 guidance and valuation explained.


Written 2026-10-02 KST. Prices refer to the 2026-10-01 US regular-session close, excluding after-hours trading.
Synopsys (SNPS) closed at $490.54, up $55.60 or 12.78%. Its investor day brought together a multi-year Amazon agreement worth more than $1 billion, an OpenAI partnership and fiscal 2027 guidance above market expectations. The announcements strengthen its earnings case, although the contribution of each catalyst to the price move cannot be isolated. Reuters report
VLSI Korea view: The rally reflects both a better earnings outlook and new ways to earn revenue from AI chip development. Further upside needs evidence that these opportunities become profitable business.
| Window / comparison date | Previous close | Latest close | Change |
|---|---|---|---|
| 1 day / 2026-09-30 | $434.94 | $490.54 | +$55.60 / +12.78% |
| 1 week / 2026-09-24 | $424.91 | $490.54 | +$65.63 / +15.45% |
| 1 month / 2026-09-01 | $414.82 | $490.54 | +$75.72 / +18.25% |
The weekly comparison uses 5 trading days; the monthly comparison uses the same calendar date one month earlier. Returns equal closing price divided by the comparison close, minus one. These are USD price returns before currency conversion, fees and taxes. Historical prices
Volume reached approximately 6.31 million shares, around 3.4 times MarketScreener's 20-session average of 1.85 million. This establishes unusually heavy trading, but does not identify institutional buying or short covering as the cause. Volume data
Shares gained 4.78% on 2026-09-30, the investor-day date. From the 2026-09-29 close through 2026-10-01, the gain was 18.18%. This two-session reaction cannot explain the entire preceding month. Daily closes
Synopsys supplies EDA software for chip design and verification, reusable semiconductor IP, and simulation and analysis tools. IP here means design assets customers can incorporate into chips. The investment argument is that more ambitious AI chips can increase demand for the tools and building blocks needed to design and verify them. Company announcement
The Amazon agreement matters for its license-plus-royalty structure, as well as its size. Amazon is the lead customer for an expansion into application-optimized IP. The collaboration also covers EDA, simulation and AI engineering tools. Amazon agreement
The business interpretation is that design participation could generate revenue beyond the initial license as customers expand production. But the total contract value is neither annual revenue nor guaranteed profit. The announcement does not provide a complete annual recognition schedule, royalty rate or breakdown of guaranteed and variable consideration. Adding the entire contract to fiscal 2027 guidance could double-count expectations already included.
| Agreement | Disclosed mechanism | Not quantified in the release |
|---|---|---|
| Amazon | Multi-year, $1B+; license + royalty | Annual revenue schedule; royalty rate |
| OpenAI | EDA licensing; planned joint service and revenue sharing | Revenue amount; commercial adoption scale |
OpenAI and Synopsys plan to develop GPT-Synopsys, a specialized model that operates Synopsys tools. The agreement includes EDA licensing, joint commercialization and revenue sharing. The planned service bundles compute, models and licenses; the companies say early technology engagements with semiconductor customers are underway. OpenAI partnership
If AI automates design while still relying on established tools to compute and verify results, Synopsys can remain part of the revenue chain. Agents exploring more alternatives could increase tool consumption. That is an inference, not demonstrated customer revenue growth. The key commercial question is whether higher productivity reduces customer spending or expands design activity and paid usage.
Fiscal 2027 guidance provides the clearest numerical support for the rally. The fiscal year ends 2027-10-31.
| Metric | Company outlook | Comparison / definition |
|---|---|---|
| Revenue | $11.10B-$11.20B | $11.15B midpoint vs $10.81B consensus: +3.15% |
| Adjusted EPS | $19.04-$19.12 | $19.08 midpoint vs $17.81 consensus: +7.13% |
| Operating margin | 44.0% adjusted | 20.7% GAAP |
| Free cash flow | Approximately $3.10B | Company forecast, not realized cash flow |
Company figures come from its investor-day release. Consensus figures are LSEG estimates reported by Reuters.
EPS guidance exceeds expectations by more than revenue guidance does. That supports a stronger adjusted-earnings outlook, reflecting operating margins, interest, taxes and share-count assumptions. Management also targets approximately 15% annual revenue growth through fiscal 2030 and a roughly 50% adjusted operating margin, and intends to repurchase around $1 billion of shares in coming months. These are objectives and plans, not achieved results. Reuters
At $490.54, the stock trades at approximately 25.7 times the fiscal 2027 adjusted EPS midpoint of $19.08. Using the GAAP midpoint of $8.385 instead gives 58.5 times. Acquired-intangible amortization, stock compensation, restructuring and tax adjustments explain the difference. A valuation discussion based only on adjusted earnings can miss the economic significance of excluded costs. Reconciliation
| Assumed P/E | Calculated price | Change from $490.54 |
|---|---|---|
| 22x | $419.76 | -14.43% |
| 26x | $496.08 | +1.13% |
| 30x | $572.40 | +16.69% |
This is an illustrative sensitivity calculation with adjusted EPS fixed at $19.08. The multiples are assumptions, not estimates of fair value or price targets. The company can meet guidance while its stock falls if investors pay a lower multiple. Additional earnings upgrades or more confidence in durable growth could support the opposite outcome.
The existing business also needs a careful reading. Fiscal 2026 third-quarter revenue was $2.477 billion, up approximately 42.4% from $1.740 billion. Ansys changes the scope of the comparison; the company's full-year outlook includes $2.98 billion of expected Ansys revenue. Reported growth should not be treated as organic growth. Quarterly results
| Case | Business condition | Evidence to monitor |
|---|---|---|
| Upside | Contracts monetize; paid AI usage grows | Royalty contribution; earnings upgrades |
| Consolidation | Execution meets guidance without upgrades | Guidance retention; trading stabilization |
| Downside | Monetization delayed; costs or restrictions increase | Revenue timing; margins; cash conversion |
A continued rally would be supported by contract revenue and royalties, measurable paid AI adoption and further earnings upgrades. Spending and profitability per customer would be more informative than customer counts alone. A pause or partial reversal is plausible if execution meets guidance without further upgrades after the sharp repricing.
The downside case strengthens if monetization takes longer, customers postpone design spending, or integration costs and export restrictions pressure results. Customer concentration, export controls and Ansys integration are company-disclosed risks, not evidence that these adverse outcomes have already occurred. Risk discussion
The medium-term business outlook has improved; additional returns after the jump need further earnings evidence. The next earnings update should clarify fiscal 2027 guidance, IP and royalty contribution, disclosed AI monetization, cash flow and share-count changes.
Related: How EDA tools are priced
Disclosure
This article is provided for informational purposes only and does not constitute a recommendation to buy or sell any security. Figures and factual statements are based on publicly available sources, including company filings, news reports, and market research, and may contain errors in the source material or in the preparation of this article. The author may own shares in companies mentioned. All investment decisions and their outcomes are the reader's responsibility.



