VLSI Korea
SOX Closes Up 0.44% on October 23 as SK hynix Gains 4.42% — the HBM Lead-Change Estimate and 8 Reads
The SOX closed up 0.44% on October 23, recovering part of the prior drop, while SK hynix gained 4.42% after halting the Solidigm listing review. The Bernstein HBM revenue estimate and next week's earnings calendar, in 8 reads.


Start with the conclusion. On October 23, 2026, the Philadelphia Semiconductor Index (SOX) closed up 0.44% at 10,779.46 — a partial recovery from the prior session's 6.72% drop. The Nasdaq fell 0.21% to 25,955.34 and the S&P 500 fell 0.52% to 7,623.68. In Korea the same day, SK hynix closed up 4.42% at 1,277,000 won and Samsung Electronics rose 0.47% to 215,500 won. SK hynix disclosed that it has halted its review of a Solidigm listing. AllianceBernstein estimated Samsung's third-quarter HBM revenue at USD 8.7 billion, ahead of SK hynix at USD 7.6 billion. Here are 8 reads for today.
Market Snapshot — 10:40 KST, October 24, 2026 US close (October 23): SOX +0.44% · Nasdaq -0.21% · S&P 500 -0.52% Korea close (October 23): KOSPI +0.30% · KOSDAQ -1.62% · Samsung Electronics +0.47% (KRW 215,500) · SK hynix +4.42% (KRW 1,277,000) US futures (as of 10:40 KST, weekend): Nasdaq-100 futures +0.11% · S&P 500 futures -0.42% Korea today (Saturday, October 24): (market closed — next session Monday, October 26)
8 reads for today
1. US chip stocks recover part of the drop in one day — Micron leads the rebound
- US chip stocks retraced part of the prior session's losses intraday on October 23. Micron rose 3.47% to USD 886.22 and SK hynix's US-listed shares gained 4.49% to USD 137.60 (intraday figures).
- AMD rose 1.97%, Intel 2.13% and Broadcom 0.66%, while Nvidia slipped 0.11%. On a closing basis, the SOX gained 0.44%.
- The prior drop was driven by questions over the scale and returns of AI investment, with Meta's cash-flow burden and data-center financing costs at the center of the debate.
Chase's take: The order of the rebound matters more than its size. Memory moved first, which says the market is questioning price and financing, not AI demand itself. If demand had cracked, Micron would have recovered last, not first.
2. SK hynix halts the Solidigm listing review — Korea close up 4.42%
- In a disclosure before the open on October 23, SK hynix said Solidigm had reviewed pre-IPO fundraising and an IPO to expand capacity and competitiveness, but decided to halt the review after weighing capital-market conditions.
- SK hynix fell as much as 4.25% intraday early in the session, then recovered on bargain buying to close up 4.42% at 1,277,000 won. Samsung Electronics rose 0.47% to 215,500 won.
- Market commentary credited the removal of listing uncertainty for part of the sentiment recovery.
Chase's take: A listing raises cash, but it also underwrites future NAND supply growth. Halting it is friendlier to NAND pricing in the short term and removes an overhang for shareholders. If next week's earnings add buyback or dividend language, the meaning of this decision becomes complete.
3. AllianceBernstein estimate — Samsung passes SK hynix in Q3 HBM revenue
East Asia Brief, October 23, 2026
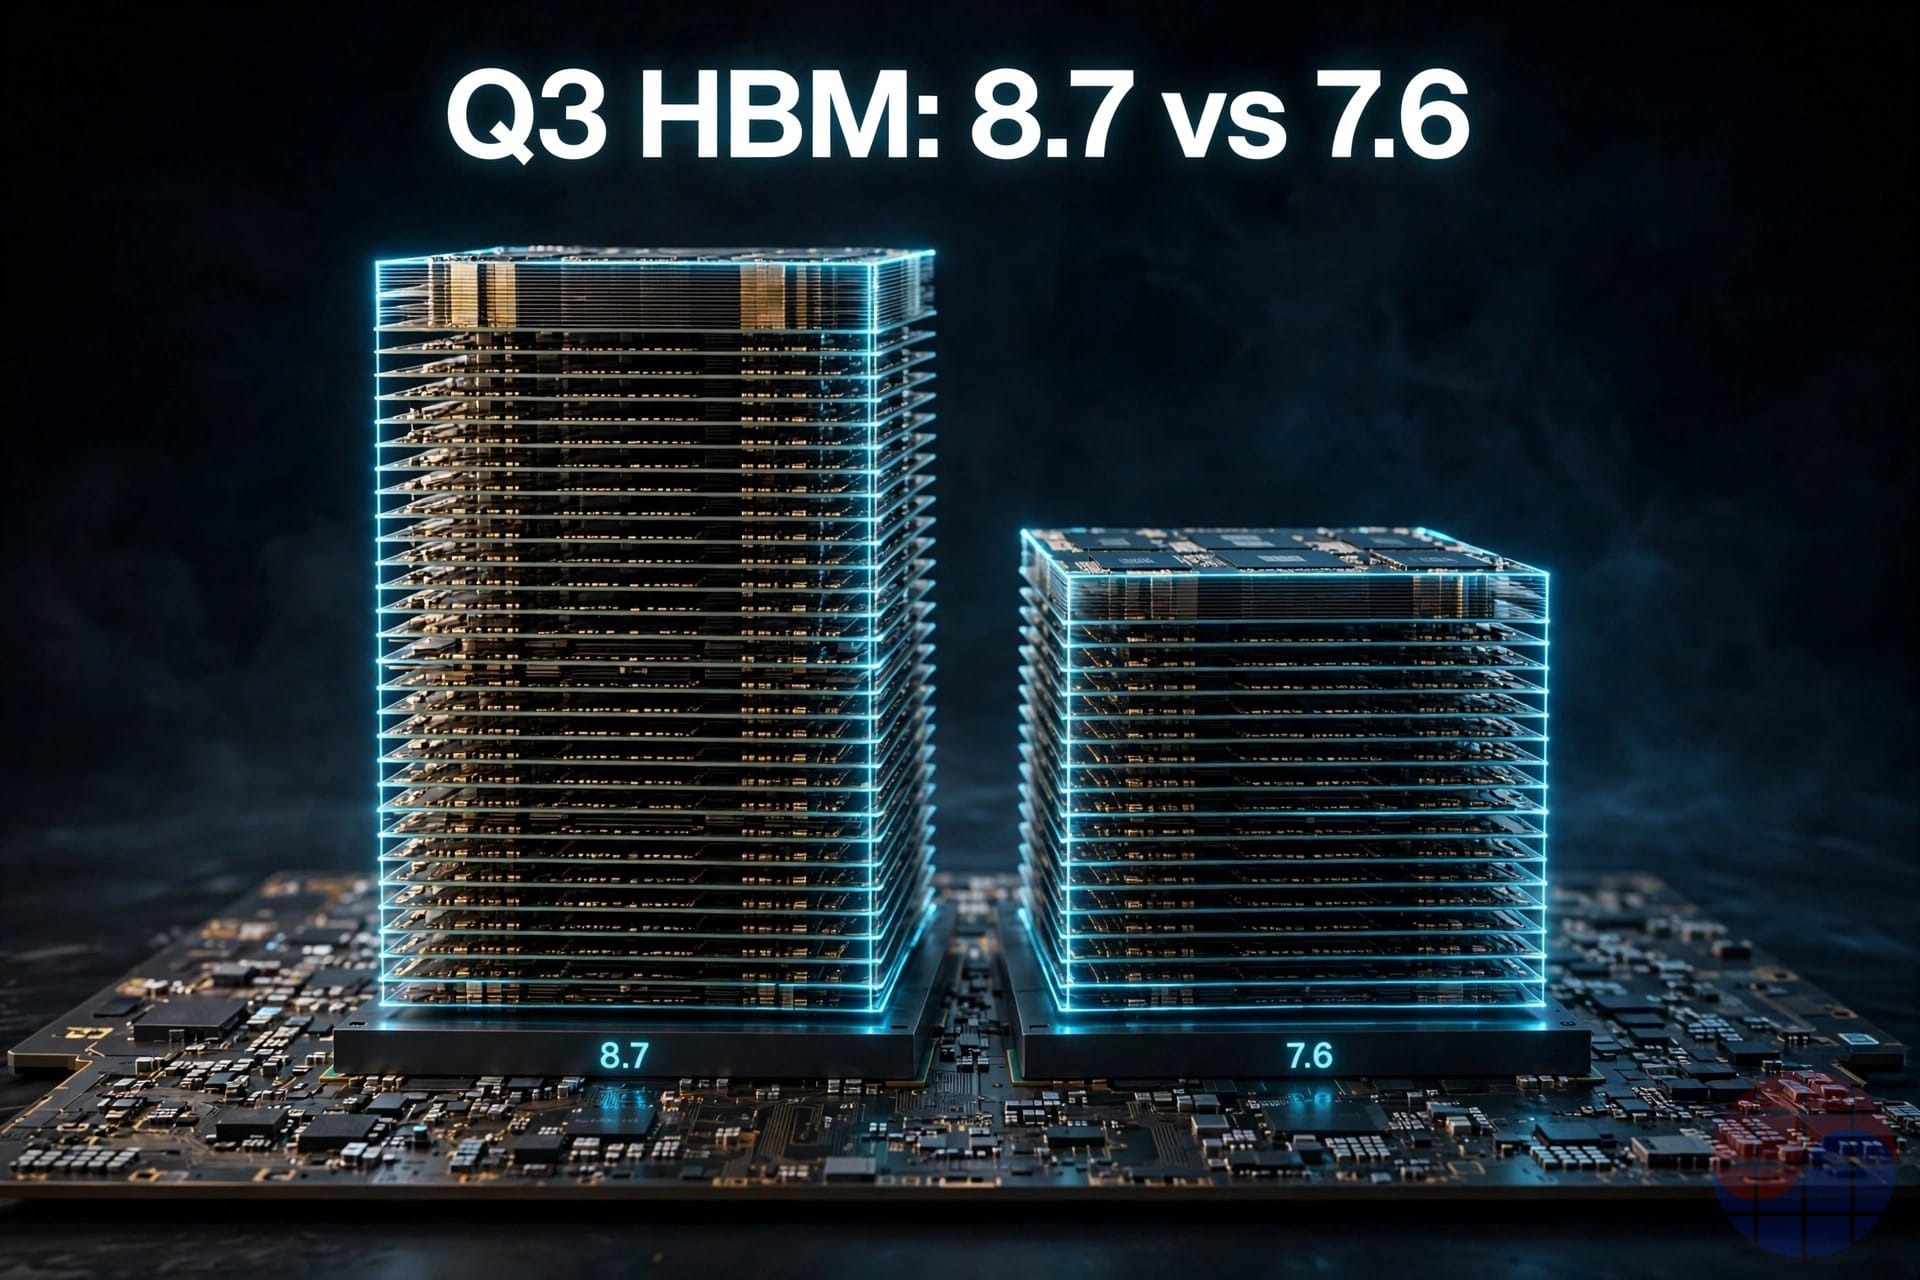
- AllianceBernstein estimated Samsung Electronics' third-quarter HBM revenue at USD 8.7 billion, up 33% from the prior quarter.
- Its estimate for SK hynix over the same period was USD 7.6 billion. If correct, this is the first change at the top of quarterly HBM revenue in the current AI cycle.
- Confirmed results arrive next week: SK hynix reports on October 28 and Samsung Electronics on October 29.
Chase's take: These are estimates, and confirmed earnings will test them. The direction, however, matches the price data covered yesterday. When Samsung's HBM shipments and commodity DRAM prices improve in the same quarter, the revenue ranking can move. More important than the flip is that combined HBM revenue keeps growing.
4. Korea as Nvidia's second advanced-packaging hub — Amkor Gwangju and substrate investment
GoBull analysis (Medium), October 23, 2026
📩 Following this story?
Get the follow-up analysis — earnings, reports and HBM supply — in your inbox daily at 10:30 KST. Subscribe free →
- According to the analysis, Amkor's Korean unit runs three sites (Songdo, Bupyeong, Gwangju) with about 8,400 employees, and a new Gwangju line broke ground on October 19, with KRW 3 trillion of investment planned for 2026–2031.
- Amkor targets an increase of more than 300% in Korean interposer wafer capacity by the end of 2028. A plant takes about 12 months to build in Korea versus about 30 months in the US, the analysis says.
- SEMCO is investing KRW 4.27 trillion in its Sejong FC-BGA plant, with mass production planned for September 2028. The analysis argues Korea is the only region outside Taiwan with HBM, interposer packaging, substrates and bonding equipment in one place.
Chase's take: Packaging is no longer a back-end step; it is the bottleneck. When the country that makes HBM also adds the packaging, the center of gravity in the supply chain moves. The Gwangju groundbreaking and the Sejong investment are that move, already funded.
5. Micron's Taiwan union stages the chip sector's first strike — 24 hours on October 22
AI News Brief, October 23, 2026
- Micron's Taoyuan union walked out for 24 hours on October 22, in what was reported as Taiwan's first semiconductor-sector strike.
- The union reportedly rejected a 68-month bonus offer and sought a permanent 15% share of operating profit. A separate Taichung union had already settled.
- It is a case of profit-sharing conflict reaching the production floor while AI memory demand lifts earnings.
Chase's take: Timing matters more than the strike itself. A labor issue surfacing when HBM capacity is tightest reads as a supply-risk premium. If it grows, it also feeds customers' supply-diversification discussions.
6. Earnings week ahead — SK hynix on the 28th, Samsung and Intel on the 29th
jorgai Intel earnings preview, October 21, 2026
- SK hynix reports confirmed third-quarter results on October 28, Samsung Electronics on October 29, and Intel after the US close on October 29.
- Intel's own guidance is third-quarter revenue of USD 15.8–16.8 billion and non-GAAP EPS of USD 0.38. Consensus sits near USD 16.5 billion of revenue and USD 0.37–0.40 of EPS — roughly at guidance.
- A Federal Reserve rate decision lands in the same week. With earnings and rates stacked together, volatility itself should be the base case.
Chase's take: Next week has one question. How far did higher prices carry earnings, and do fourth-quarter comments defend those prices? For the two Korean names, watch HBM mix and commodity pricing; for Intel, the foundry loss line.
7. Anthropic hands Agent Skills to a neutral foundation — agent standards move house
AI News Brief, October 23, 2026
- On October 22, Anthropic donated Agent Skills to the Agentic AI Foundation, which has also taken in agent-interoperability standards such as MCP and OpenAI's AGENTS.md.
- A pattern is repeating: widely adopted agent standards move from their creator's roof to neutral governance.
- For semiconductors, this widens the base of token demand. As agent workloads accumulate on shared standards, inference compute demand is not trapped inside one model company's app.
Chase's take: Neutral standards accelerate adoption, and adoption brings compute demand with it. The distance between a software-governance headline and a memory order keeps getting shorter.
8. Oil and rates — WTI above USD 100, the 10-year near 5%
Curve Ahead Market Strategies, October 23, 2026
- Intraday on October 23, WTI rose 3.51% to USD 102.96 a barrel and Brent reached USD 116.99.
- The US 10-year Treasury yield was 4.994%, just below 5%, and the VIX was 19.42.
- Rising energy prices and rates together push up both data-center power costs and financing costs — the combination sitting behind this week's chip-stock debate.
Chase's take: The AI-returns debate is really a cost debate. If electricity and interest rates move before chip prices do, data-center project economics wobble regardless of chip performance.
Semiconductor stocks wrap (confirmed closes only)
| Session | Name | Move | Note |
|---|---|---|---|
| US close (Oct 23) | SOX | +0.44% | 10,779.46 |
| US close (Oct 23) | Nasdaq | -0.21% | 25,955.34 |
| US close (Oct 23) | S&P 500 | -0.52% | 7,623.68 |
| Korea close (Oct 23) | SK hynix | +4.42% | KRW 1,277,000 |
| Korea close (Oct 23) | Samsung Electronics | +0.47% | KRW 215,500 |
| Korea close (Oct 23) | KOSPI | +0.30% | 5,550.30 |
| Korea close (Oct 23) | KOSDAQ | -1.62% | 751.69 |
| US futures (Oct 24, 10:40 KST) | Nasdaq-100 futures | +0.11% | weekend snapshot |
| US futures (Oct 24, 10:40 KST) | S&P 500 futures | -0.42% | weekend snapshot |
Note: KOSPI closed up 0.30% at 5,550.30 and KOSDAQ fell 1.62% to 751.69 on October 23 (added after a re-check at publication time). Index and stock closes are calculated from daily bars by market_snapshot.py.
Frequently asked questions
📩 Missed today's analysis? Get tomorrow's in your inbox
Daily Silicon at 10:30 KST plus earnings and analyst-report breakdowns, first. Samsung Electronics, SK hynix, TSMC and HBM supply, read by practicing engineers. Join 300+ subscribers.
Subscribe free →
Free · No spam · Unsubscribe anytime