VLSI Korea
DISCO Earnings: Record Sales, a Stock at Its Year Low — Shipments of JPY 148.7B and the Guidance Gap (DISCO, HBM Back-End)
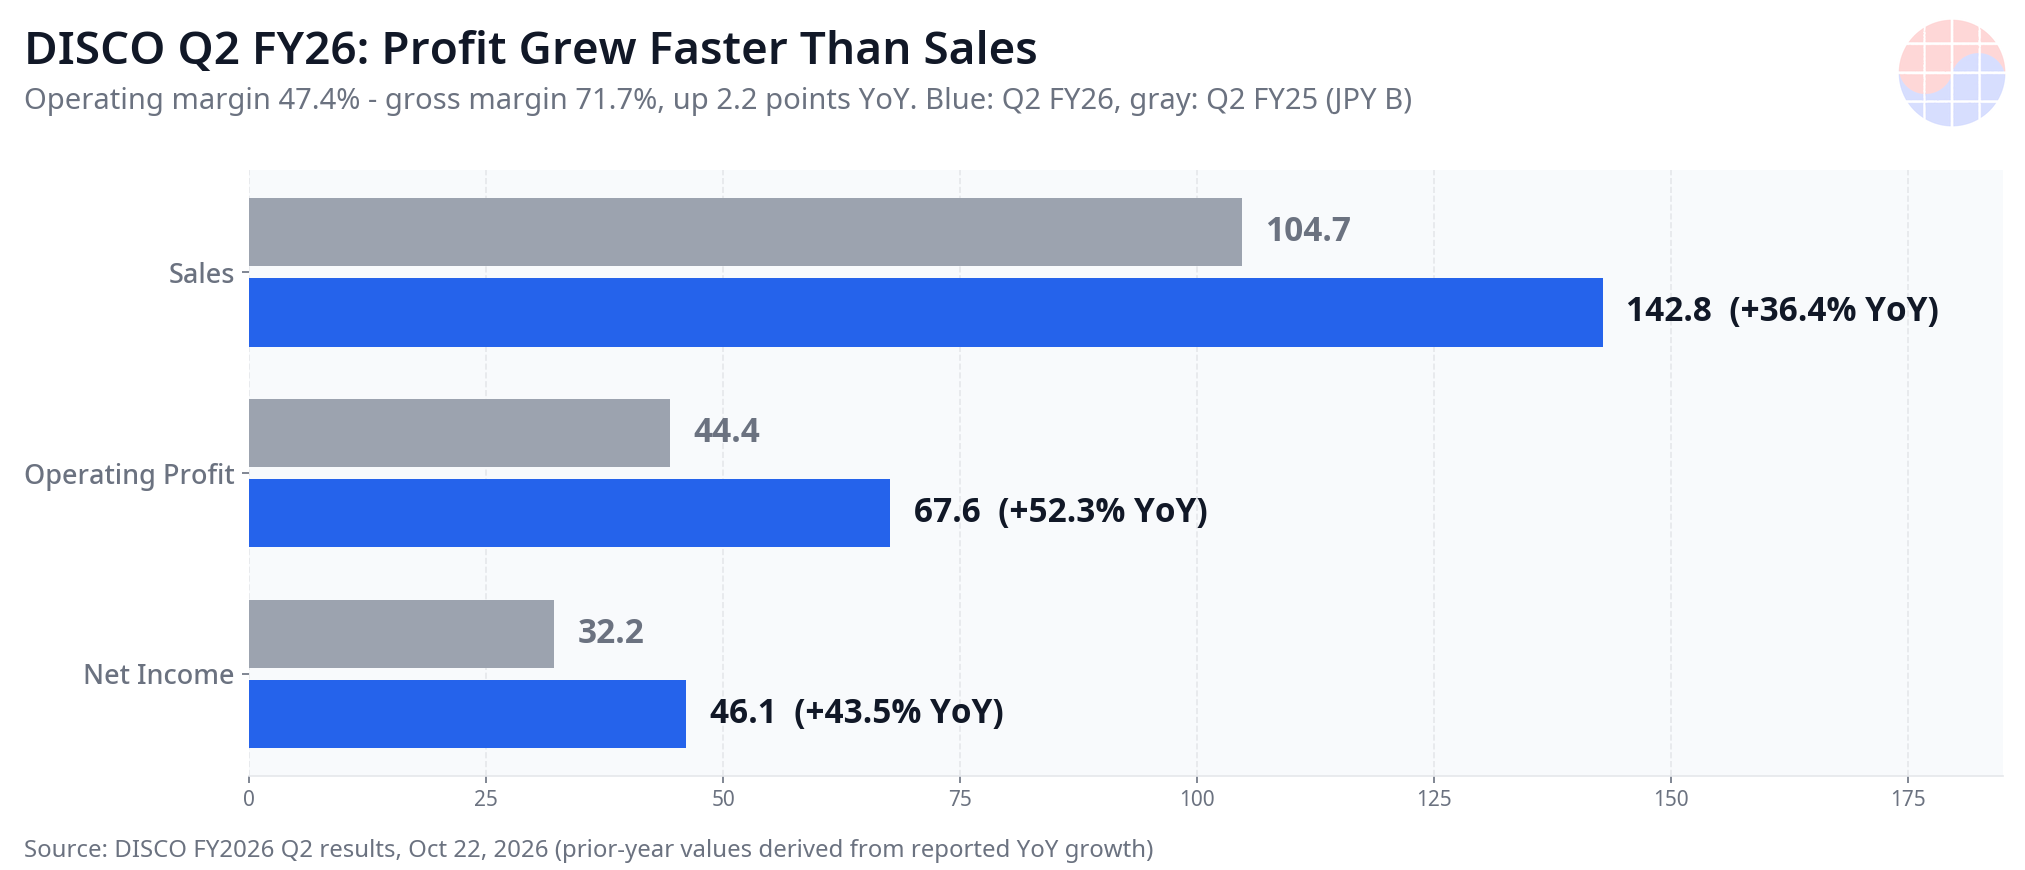
DISCO posted record fiscal Q2 2026 sales of JPY 142.75B (up 36.4%), operating profit of JPY 67.6B (up 52.3%) and record shipments of JPY 148.7B (up 54%) — yet the stock hit a year-to-date low, because its first nine-month outlook implies next-quarter operating profit about JPY 10B below consensus.


🆓 Free article · Anyone can read this article for free
Bottom line first. DISCO (TSE: 6146) reported fiscal Q2 2026 (July-September 2026) results on October 22 with record quarterly sales of JPY 142.75 billion (up 36.4% year over year) and operating profit of JPY 67.6 billion (up 52.3%), while shipments — the cleanest demand gauge DISCO publishes — hit a record JPY 148.68 billion, up 54%. Yet on October 23 the stock fell as much as 10% intraday to a new year-to-date low. The reason was not the quarter. It was the company's first nine-month outlook, which implies October-December operating profit of roughly JPY 58.1 billion, close to JPY 10 billion below market expectations. With today's earnings meeting complete, here is how to read the gap.
Figures are from the company's October 22, 2026 results release, cross-checked across multiple Japanese outlets. Guidance-versus-consensus comparisons are from Japanese market reporting on October 23, and the share price is the October 23 Tokyo close.
The numbers at a glance
| Item | Q2 (Jul-Sep) result | Year over year |
|---|---|---|
| Sales | JPY 142.75B | +36.4% (quarterly record) |
| Operating profit | JPY 67.6B (47.4% margin) | +52.3% (record) |
| Net income | JPY 46.1B | +43.5% |
| Gross margin | 71.7% | +2.2 points |
| Shipments | JPY 148.68B | +54% (record) |
| H1 (Apr-Sep) sales / operating profit | JPY 257.1B / JPY 116.6B | +32.1% / +47.9% |
| Oct-Dec shipment outlook | JPY 149.6B | Above the record Q2 |
| Oct-Dec operating profit (implied) | ~JPY 58.1B | ~JPY 10B below consensus |
| Interim dividend | JPY 186 per share | Raised JPY 15 (JPY 129 a year ago) |
| Share price (Oct 23 close) | JPY 49,290 | -3.79% (intraday -10%, YTD low) |
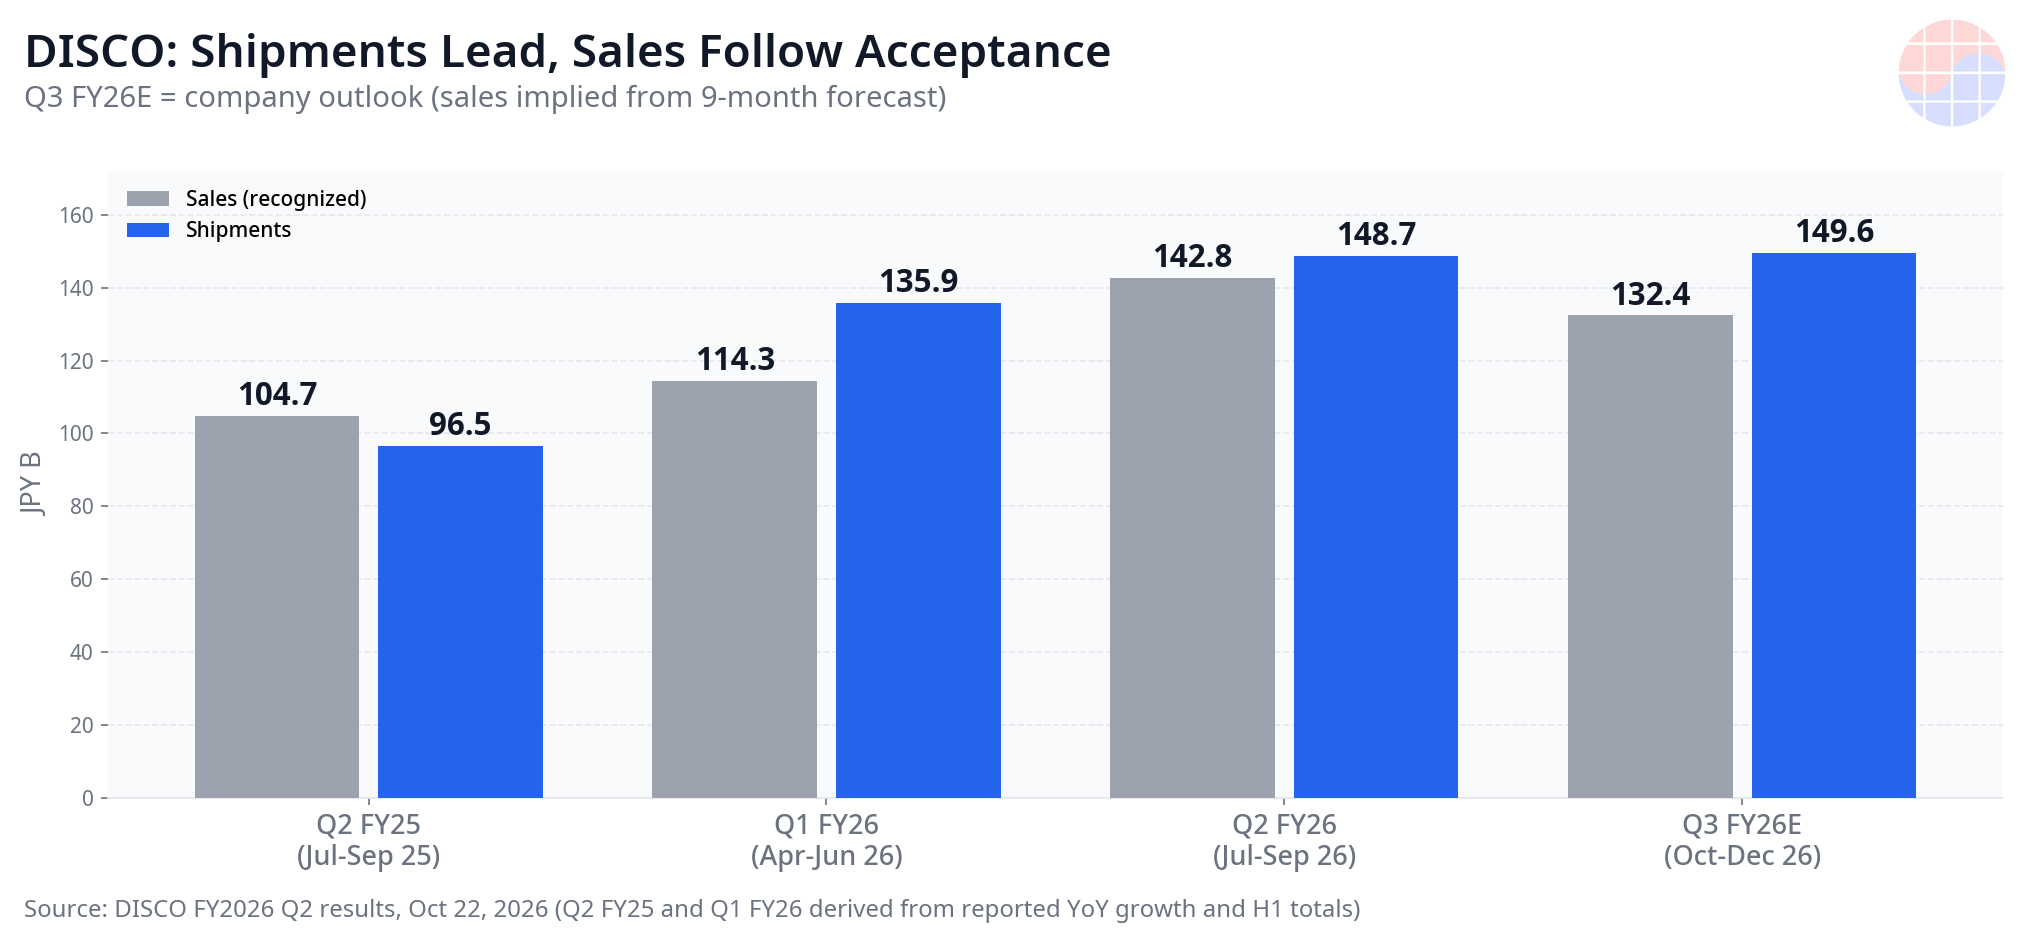
Shipments keep setting records and the October-December outlook of JPY 149.6B is higher still. Sales are recognized on customer acceptance, so they trail shipments. Source: DISCO fiscal Q2 2026 results, October 22, 2026.
What split — a beat in the quarter, a miss in the guide
July-September operating profit of JPY 67.6 billion beat market expectations by roughly JPY 2 billion; Japanese market reporting attributes the upside to stronger-than-expected consumables (precision processing tools) and better margins. The problem is the next quarter. Because demand swings quickly, DISCO only guides one quarter ahead. Its newly disclosed nine-month (April-December) outlook — sales of JPY 389.5 billion (up 28.2%) and operating profit of JPY 174.7 billion (up 38.4%) — implies October-December operating profit of about JPY 58.1 billion once the first half is subtracted, roughly JPY 10 billion below a consensus near JPY 68 billion.
A domestic analyst quoted by Reuters on October 23 put it plainly: current results were very strong, but the Q3 outlook landed below expectations and selling came first — with the caveat that the company habitually guides conservatively, so the market may be overreacting. The stock touched JPY 46,100 intraday, a new year-to-date low, before closing at JPY 49,290, down 3.79%.
The demand underneath — HBM, consumables, and CPO
Generative AI drove the equipment shipments. Memory equipment rose around HBM, and logic demand stayed high on AI applications. HBM stacks multiple DRAM dies, so the precision of wafer thinning (grinding) and singulation (dicing) is effectively yield — and DISCO is the default toolset for both steps. Consumables shipments also set a record on high customer utilization, which says the installed base is running flat out, not just that new tools are being bought.
The new line to watch is CPO (co-packaged optics). Demand for dicers used in optical semiconductors and for optical components such as fiber arrays is starting to grow, though the company itself says it is not yet at a scale that moves results on its own the way HBM did at its start. The swing factor ahead is whether hybrid bonding and panel-level packaging move into full mass production and pull packaging processing demand with them.
📩 Following this story?
Get the follow-up analysis — earnings, reports and HBM supply — in your inbox daily at 10:30 KST. Subscribe free →
Profit grew faster than sales. The 71.7% gross margin combines a weaker yen with a richer mix of high-value tools. Source: DISCO fiscal Q2 2026 results, October 22, 2026.
Chase's Take
First, this print collides head-on with the "AI capex is slowing" narrative the market sold over the last two sessions. Lam Research's supply constraints and the Meta funding debate are front-end and financing fears. DISCO sits in the middle of the back end, and its shipments — a measured demand series that leads recognized sales by a quarter — are at a record, with a higher outlook for next quarter. The fear is about money and multiples, not about orders. That is what the back-end numbers say.
Second, the guidance gap is a recurring DISCO pattern, and it should be read that way first. The company guides only one quarter out and is known for conservative plans. The lower October-December sales outlook is an artifact of acceptance timing and a USD/JPY assumption of 151 — not shrinking shipments. The roughly JPY 10 billion gap to consensus is a gap to the company's guiding habit before it is a demand warning. That is not a free pass: if shipments actually roll over next quarter, the pattern becomes a trend.
Third, the practical link is the Korean calendar. SK hynix reports on October 28 and Samsung Electronics on October 29. DISCO's shipment mix centered on HBM is an indirect measurement that the two Korean makers' HBM output and back-end investment have not slowed. Line up their HBM and packaging commentary against DISCO's shipment curve and you can judge, with numbers, whether this week's selloff overshot.
What to check next
- SK hynix (October 28) and Samsung Electronics (October 29): whether HBM volume and packaging investment commentary points the same way as DISCO's shipments.
- DISCO's October-December shipment flash (January 2027): holding the JPY 149.6B outlook settles the guidance argument.
- The yen: guidance assumes USD/JPY 151. A stronger yen weakens one leg under the 71.7% gross margin.
Related: Citi Keeps SK hynix Target at KRW 3 Million as AI Inference Drives eSSD Demand · Western Digital Earnings: 8 Facts — Guidance Beat the 55% Revenue Jump · SK hynix Halts the Solidigm Listing: 5 Facts About the $15 Billion Financing That Vanished
FAQ
What were the key numbers in DISCO's fiscal Q2 2026 results?
Sales of JPY 142.75 billion (up 36.4% year over year), operating profit of JPY 67.6 billion (up 52.3%), and net income of JPY 46.1 billion (up 43.5%) — all quarterly records — with shipments at a record JPY 148.68 billion, up 54%. Operating profit beat market expectations by roughly JPY 2 billion.
Why did the stock hit a year-to-date low on record earnings?
The company's first nine-month outlook implies October-December operating profit of about JPY 58.1 billion, close to JPY 10 billion below market expectations. The shares fell 10% intraday to a new year-to-date low on October 23 before closing at JPY 49,290, down 3.79%.
Why does DISCO emphasize shipments over sales?
Equipment revenue is recognized when the customer accepts the tool, which makes quarterly sales lumpy. Shipments are recorded when tools actually leave, so they track demand direction more faithfully. DISCO guided October-December shipments to JPY 149.6 billion — above the record quarter just reported.
What does DISCO's result signal for Korean chipmakers?
With shipment growth centered on HBM-related memory equipment, it is indirect confirmation that HBM production and back-end investment at the two Korean memory makers have not slowed. The comparison to make is their HBM commentary when SK hynix reports on October 28 and Samsung Electronics on October 29.
Sources
DISCO fiscal 2026 second-quarter results (released October 22, 2026; earnings meeting October 23) — figures cross-checked across multiple Japanese outlets. Guidance-versus-consensus comparison from Japanese market reporting (October 23, 2026); analyst comment via Reuters (October 23, 2026); closing price from Finnhub (Tokyo close, October 23, 2026). This article is for information only and is not investment advice.
📩 Missed today's analysis? Get tomorrow's in your inbox
Daily Silicon at 10:30 KST plus earnings and analyst-report breakdowns, first. Samsung Electronics, SK hynix, TSMC and HBM supply, read by practicing engineers. Join 300+ subscribers.
Subscribe free →
Free · No spam · Unsubscribe anytime