VLSI Korea
Western Digital Earnings: 8 Facts — Guidance Beat the 55% Revenue Jump
Western Digital's fiscal Q1 2027 revenue rose 55% to USD 4,381M with non-GAAP EPS of USD 4.64, beating consensus — and Q2 guidance (USD 5.1B revenue, USD 5.80 EPS, 60.5% gross margin) beat it by more. The 8 facts and an expert read.


🆓 Free article · Anyone can read this article for free
The conclusion first. Western Digital (WD, Nasdaq: WDC) reported fiscal Q1 2027 results (quarter ended October 2, 2026) after the US close on October 22, 2026, beating consensus on both revenue and earnings — and its guidance for the next quarter cleared consensus by an even wider margin. On a day when the semiconductor index fell 5.4%, these numbers confirm that AI data center spending does not stop at GPUs and HBM: it reaches the storage layer where the data actually accumulates.
All figures below come from the company's own release (distributed via BusinessWire on October 22, 2026). Consensus figures are FactSet estimates, and the pre-earnings Wall Street view references Morgan Stanley as reported by Edaily on October 22, 2026.
The headline numbers
| Item | Actual / Guidance | Consensus | Result |
|---|---|---|---|
| Q1 revenue | USD 4,381M | USD 4,150M | Beat |
| Q1 non-GAAP EPS | USD 4.64 | USD 4.10 | Beat |
| Q1 non-GAAP gross margin | 58.1% | Company guide 55-56% | Beat |
| Q2 revenue guidance | USD 5.1B (midpoint) | USD 4.57B | +11.6% |
| Q2 non-GAAP EPS guidance | USD 5.80 (midpoint) | USD 4.84 | +19.8% |
| Q2 non-GAAP gross margin guidance | 60.5% (midpoint) | - | +2.4pp vs Q1 |
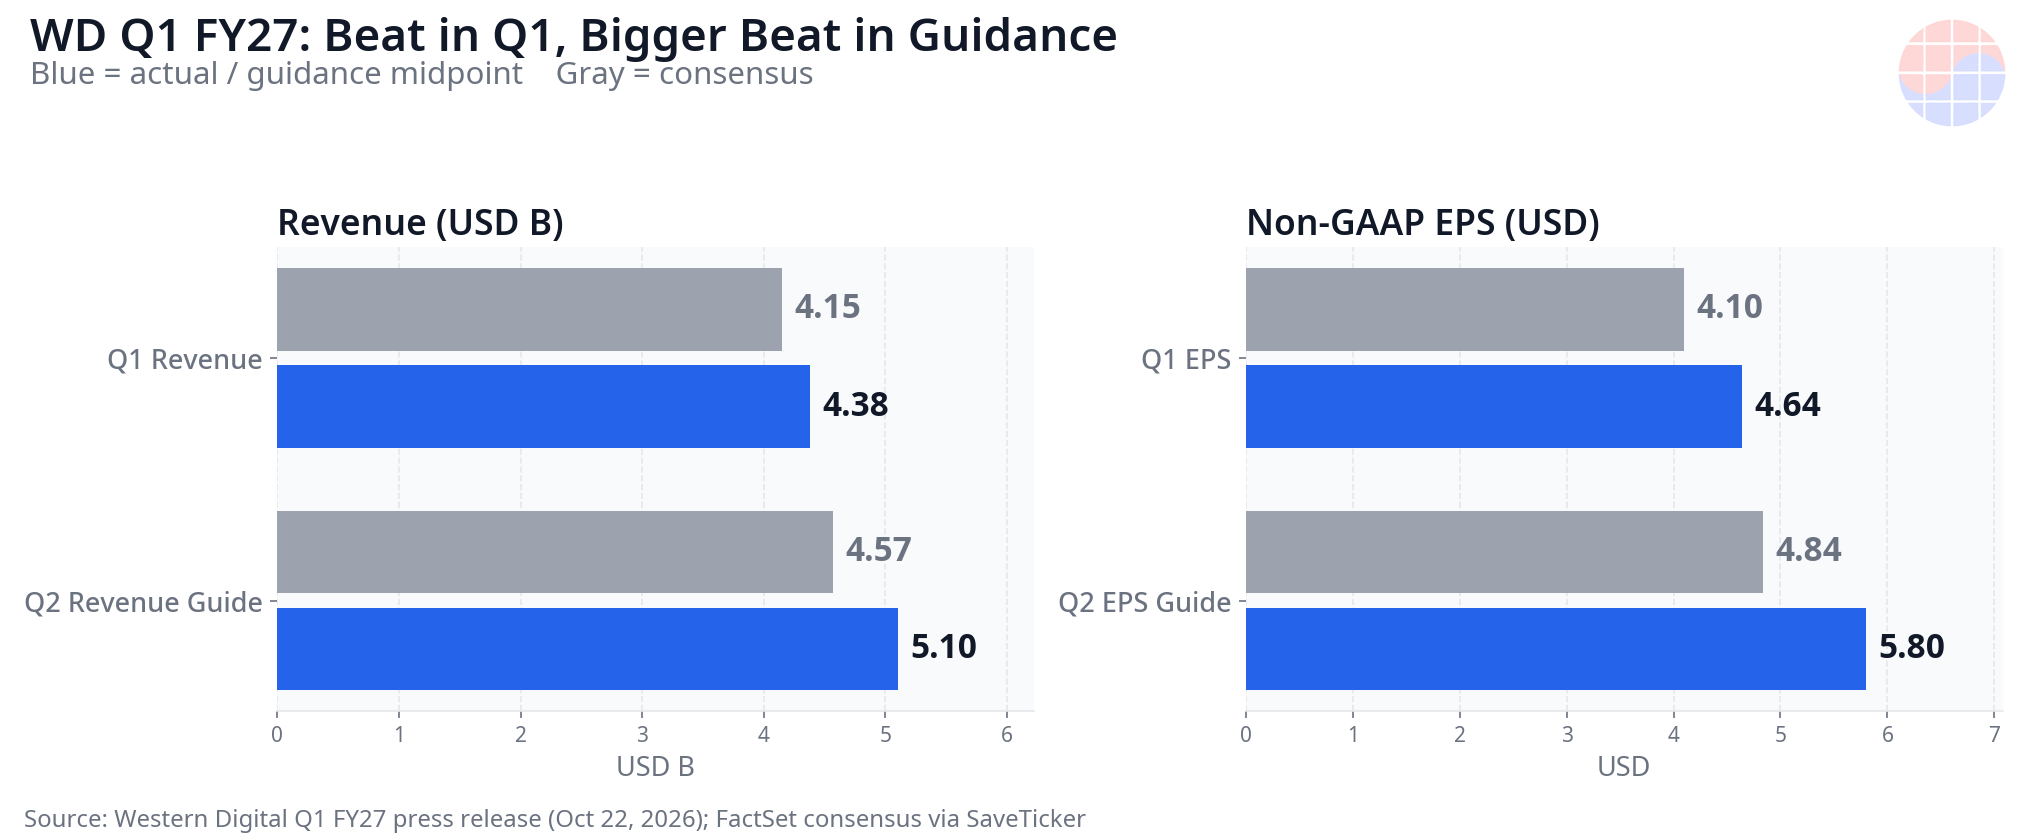
Both the reported quarter and the guidance sit above consensus. Source: company release, FactSet consensus.
Western Digital earnings: 8 facts
- Revenue of USD 4,381M, up 55% year over year. Revenue also rose 17% sequentially and cleared the USD 4,150M consensus. A year ago, the same quarter produced USD 2,818M.
- Non-GAAP EPS of USD 4.64, up 161% year over year. That beat both the USD 4.10 consensus and the company's own USD 4.00 guidance (plus or minus USD 0.15). GAAP EPS was USD 4.63.
- Non-GAAP gross margin of 58.1%. That is 14.2 percentage points above the 43.9% of a year ago, and above the top end of the company's 55-56% guidance range. The company credited robust customer demand and improved pricing.
- Non-GAAP operating income of USD 2,153M, up 152% year over year. The non-GAAP operating margin reached 49.1% — close to half of every revenue dollar now survives to operating profit.
- Next-quarter revenue guidance of USD 5.1B, plus or minus USD 100M. That is 11.6% above the FactSet consensus of USD 4.57B. The guidance beat is larger than the reported-quarter beat.
- Next-quarter EPS guidance of USD 5.80 (plus or minus USD 0.20) and gross margin guidance of 60-61%. EPS guidance sits 19.8% above the USD 4.84 consensus, and the 60.5% gross margin midpoint steps up again from Q1's 58.1%.
- Free cash flow of USD 1,377M. That is 2.3 times the USD 599M of a year ago. The company also repurchased USD 1,001M of its own shares during the quarter.
- Quarterly dividend raised 17% to USD 0.175 per share. The dividend is payable on December 17, 2026 to shareholders of record on December 4, 2026. Raising the payout alongside the results signals management confidence in the durability of the cash flow.
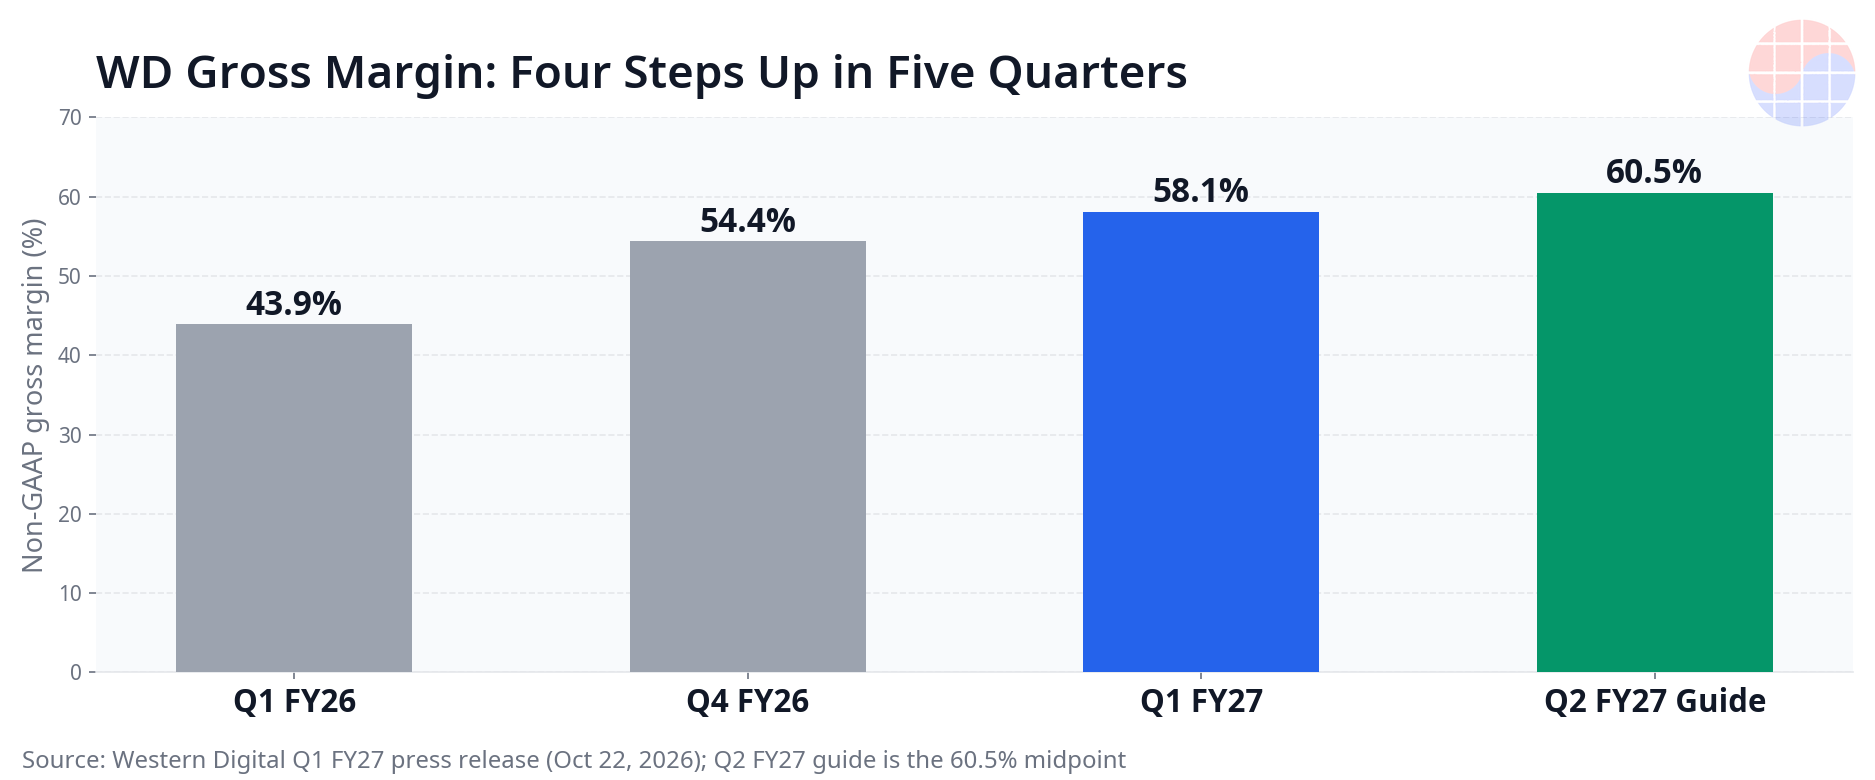
Gross margin has climbed from 43.9% to a 60.5% guidance midpoint in five quarters. Source: company release.
Chase's Take
First, this print confirms the direction of AI spending. While the market spent the day debating Lam Research's supply constraints and big-tech capex discipline — the reasons chip stocks fell — WD's numbers, released after the same close, tell the opposite story. Training data, checkpoints and inference logs have to live somewhere, and the default home for bulk data is still the nearline HDD. GPUs and HBM are bottlenecks, but storage pricing has quietly joined the bottleneck list.
Second, the story is pricing power, not unit volume. The company itself named robust demand and improved pricing as its drivers, and gross margin expanded 14.2 points in a year. HDD supply is an oligopoly shared by WD, Seagate and Toshiba, and long-term agreements with hyperscalers have turned pricing from a quarterly negotiation into an annual commitment. A 60.5% gross margin guide is the company declaring that this structure holds for another quarter.
📩 Following this story?
Get the follow-up analysis — earnings, reports and HBM supply — in your inbox daily at 10:30 KST. Subscribe free →
Third, that is exactly why the debate now shifts to whether 60% is a structure or a peak. Margins like this invite a supply response: reports ahead of this earnings season said Toshiba plans a major expansion of data center HDD capacity. Morgan Stanley, in its pre-earnings note, expected WD to beat and to guide above consensus — yet still cut its price target from USD 676 to USD 643, citing intensifying competition and AI funding uncertainty. The numbers are strong, and the numbers themselves summon the next wave of supply. That tension is the stock's story into next quarter.
What to watch next
For investors in Korean memory names, this print is a leading indicator for next week: SK hynix reports on October 28 and Samsung Electronics on October 29. Two things matter — whether enterprise SSD demand points the same way as WD's storage strength, and how the companies describe demand across storage tiers (SSDs for the hot tier, HDDs for the warm and cold tiers). Strong HDDs are not a NAND substitution signal; they are a coexistence signal. AI data is growing in both tiers at once.
Related: Why Semiconductor Stocks Are Falling: SOX -5.4% and 7 Reasons (Lam, Meta, Tesla, Power)
Risks and watch items
- Customer concentration: The first risk the company itself discloses is concentration of revenue in the cloud end market and among its top customers. A pause at a few hyperscalers can move a quarter.
- Supply response: If Toshiba's reported capacity expansion proceeds, the debate over pricing durability into 2027 intensifies.
- Rising inventories: Inventories rose from USD 1,511M on July 3 to USD 1,781M on October 2 — the line that shows stress first if demand softens.
- Cash flow detail: Free cash flow of USD 1,377M came in below the roughly USD 1.5B consensus — a number to track alongside earnings quality.
FAQ
What were the key numbers in Western Digital's fiscal Q1 2027 earnings?
Revenue of USD 4,381M (up 55% year over year) and non-GAAP EPS of USD 4.64 (up 161%), both above FactSet consensus of USD 4,150M in revenue and USD 4.10 in EPS.
What is Western Digital's guidance for the next quarter?
For fiscal Q2 2027, WD guided revenue to USD 5.1B (plus or minus USD 100M), non-GAAP EPS to USD 5.80 (plus or minus USD 0.20), and non-GAAP gross margin to 60-61% — all well above consensus of USD 4.57B and USD 4.84.
Why does an HDD maker benefit from AI spending?
AI training and inference generate enormous data volumes, and a large share of that data is stored on cost-efficient, high-capacity nearline HDDs. WD said hyperscaler demand and improved pricing lifted its gross margin to 58.1%.
What does this print signal for Samsung Electronics and SK hynix?
It confirms strong storage demand inside AI data centers. HDDs and NAND occupy different storage tiers, so the read-through is coexistence, not substitution — check the enterprise SSD commentary when SK hynix (October 28) and Samsung Electronics (October 29) report.
Sources
Western Digital, "WD Reports Fiscal First Quarter 2027 Financial Results", BusinessWire, October 22, 2026 (quarter ended October 2, 2026). Consensus: FactSet estimates as compiled by SaveTicker, October 22, 2026. Morgan Stanley view as reported by Edaily, October 22, 2026. This article is for information only and is not investment advice.
📩 Missed today's analysis? Get tomorrow's in your inbox
Daily Silicon at 10:30 KST plus earnings and analyst-report breakdowns, first. Samsung Electronics, SK hynix, TSMC and HBM supply, read by practicing engineers. Join 300+ subscribers.
Subscribe free →
Free · No spam · Unsubscribe anytime