VLSI Korea
NVIDIA의 MediaTek 35억달러 convertible: custom XPU 수익은 chip보다 NVLink attach에서 갈린다
35억달러 financing은 demand가 아닙니다. Custom XPU가 qualified rack과 recurring cash로 바뀌는 attach economics를 분석합니다.


🆓 무료 글 · 누구나 무료로 읽을 수 있는 글입니다
결론부터 말하면 NVIDIA의 MediaTek US$3.5 billion convertible은 custom XPU가 이미 US$3.5 billion의 semiconductor demand를 만들었다는 증거가 아니다. 이 거래는 NVIDIA가 customer-designed compute를 NVIDIA 중심의 system stack에 연결할 수 있는 partner에게 capital을 공급할 의지가 있다는 증거다. 앞으로 6-24개월의 investment question은 더 좁고 까다롭다. Named customer program이 architecture와 tapeout에서 package, memory, fabric, rack, acceptance, collection까지 이동하면서 두 회사 모두에게 recurring economics를 남길 수 있는가.
Public fact는 commitment를 보여주지만 핵심 unit economics는 공개하지 않는다. 2026년 8월 31일 NVIDIA와 MediaTek은 US$3.5 billion 규모의 convertible bonds와 custom XPU, NVLink Fusion, chiplet, NVLink-C2C, NVHBM, packaging, SerDes, I/O, rack integration을 포괄하는 협력을 발표했다. 그러나 두 release는 coupon, maturity, conversion price, conversion condition, named cloud customer, program volume, attach price, segment gross margin, production calendar, collection profile을 공개하지 않았다. 이 항목들은 각주가 아니다. Strategic finance와 free cash flow 사이의 evidence gap 그 자체다.
이 Research는 두 가지 reader job을 수행한다. Institutional technology investor는 ecosystem investment와 customer-funded demand를 분리하고 6-24개월 안에 반증 가능한 monitor를 만들 수 있다. Semiconductor strategy, product, supply owner는 compute die에서 HBM, chiplet, advanced packaging, SerDes, networking, optics, board, cooling, software, support로 value가 이동하는 interface를 찾을 수 있다. 결론은 security recommendation이나 price target이 아니다. Financing headline이 반복 가능한 semiconductor economics로 바뀌는 시점을 판단하는 decision framework다.
VLSI Korea view: Convertible의 핵심은 custom-XPU stack의 coordination cost를 낮출 가능성이다. Independent customer program, qualified rack, recognized revenue, collected cash가 보이기 전에는 recurring demand의 증거로 계산하지 않는다.
1. Narrative보다 balance sheet에서 시작한다
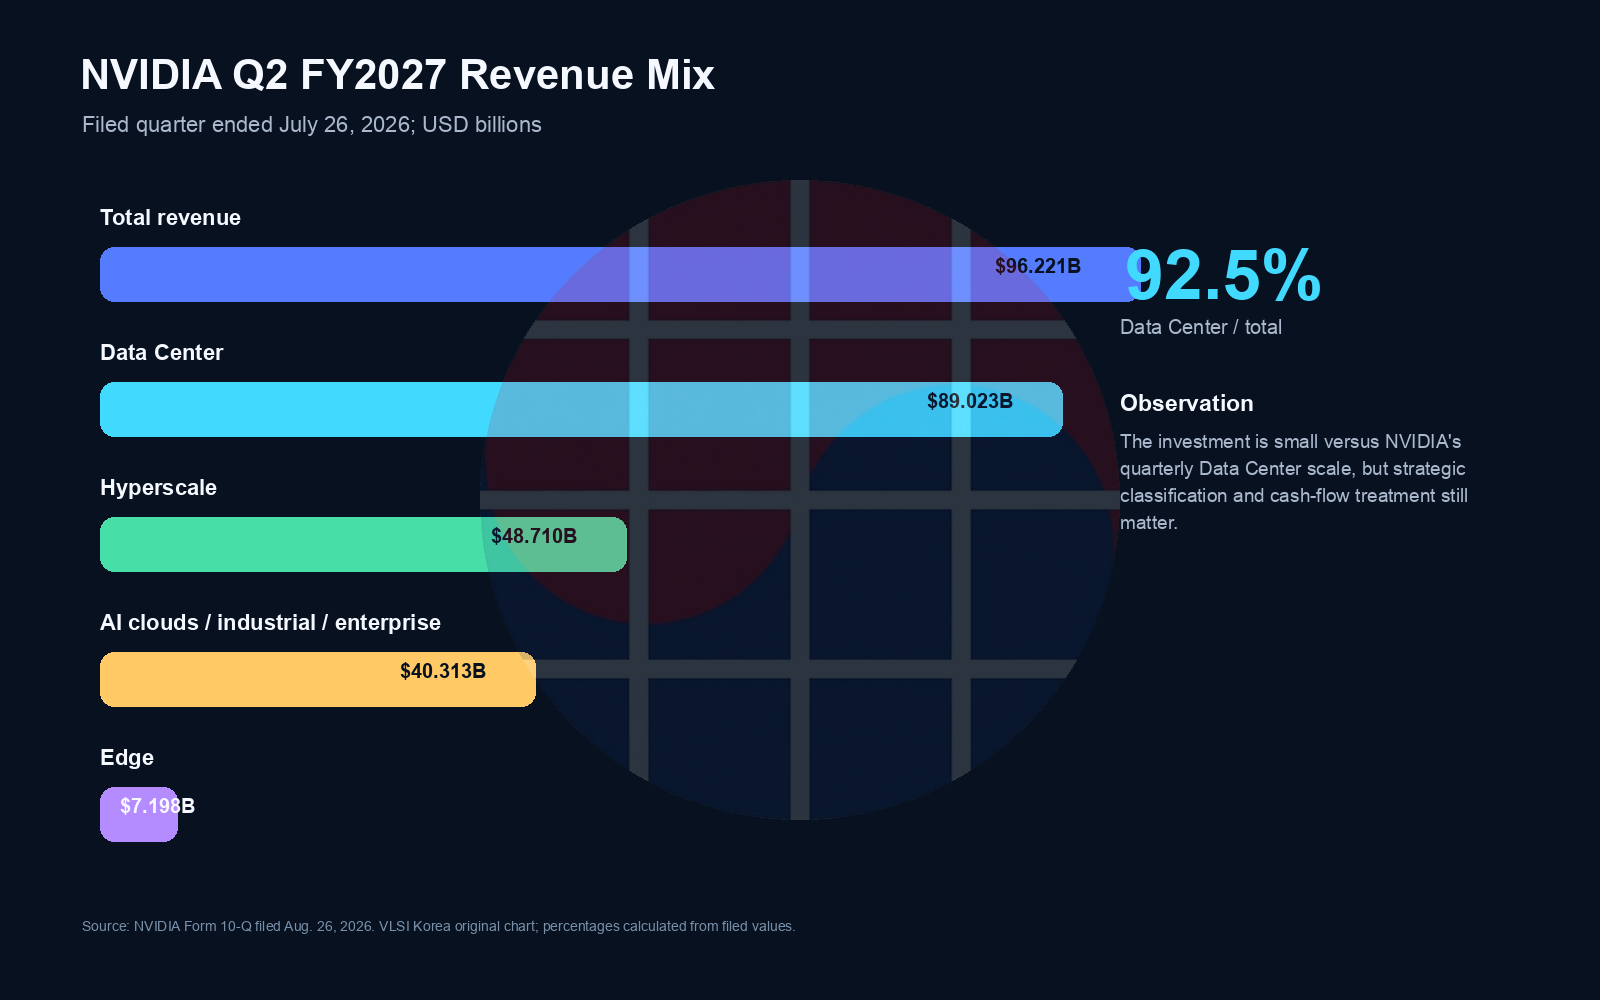
NVIDIA의 filed financial baseline은 거래를 보는 scale을 바꾼다. 2026년 7월 26일 종료 분기 Form 10-Q에 따르면 total revenue는 US$96.221 billion, Data Center revenue는 US$89.023 billion이었다. Filing은 Data Center를 hyperscale US$48.710 billion과 AI cloud, industrial, enterprise US$40.313 billion으로 나누며, edge revenue US$7.198 billion도 제시한다. Consolidated gross margin은 75.0%였다. Cash, cash equivalents, marketable debt securities는 US$56.586 billion이고 marketable equity securities는 US$42.8 billion이었다.
이 규모를 보면 US$3.5 billion convertible은 NVIDIA에게 생존을 위한 financing이 아니다. Capital allocation choice다. 같은 filing에서 first half operating cash flow는 US$74.421 billion, equity securities purchase는 US$42.404 billion이었다. MediaTek instrument는 결국 더 큰 strategic-investment activity 안에서 classification과 measurement가 이뤄져야 한다. 다음 확인 항목은 NVIDIA에서 실제로 언제 얼마의 cash가 나가는지, 언제 conversion이 가능한지, instrument가 earnings 또는 다른 accounting line을 통해 mark되는지, bond 외에 추가 commercial commitment가 있는지다.
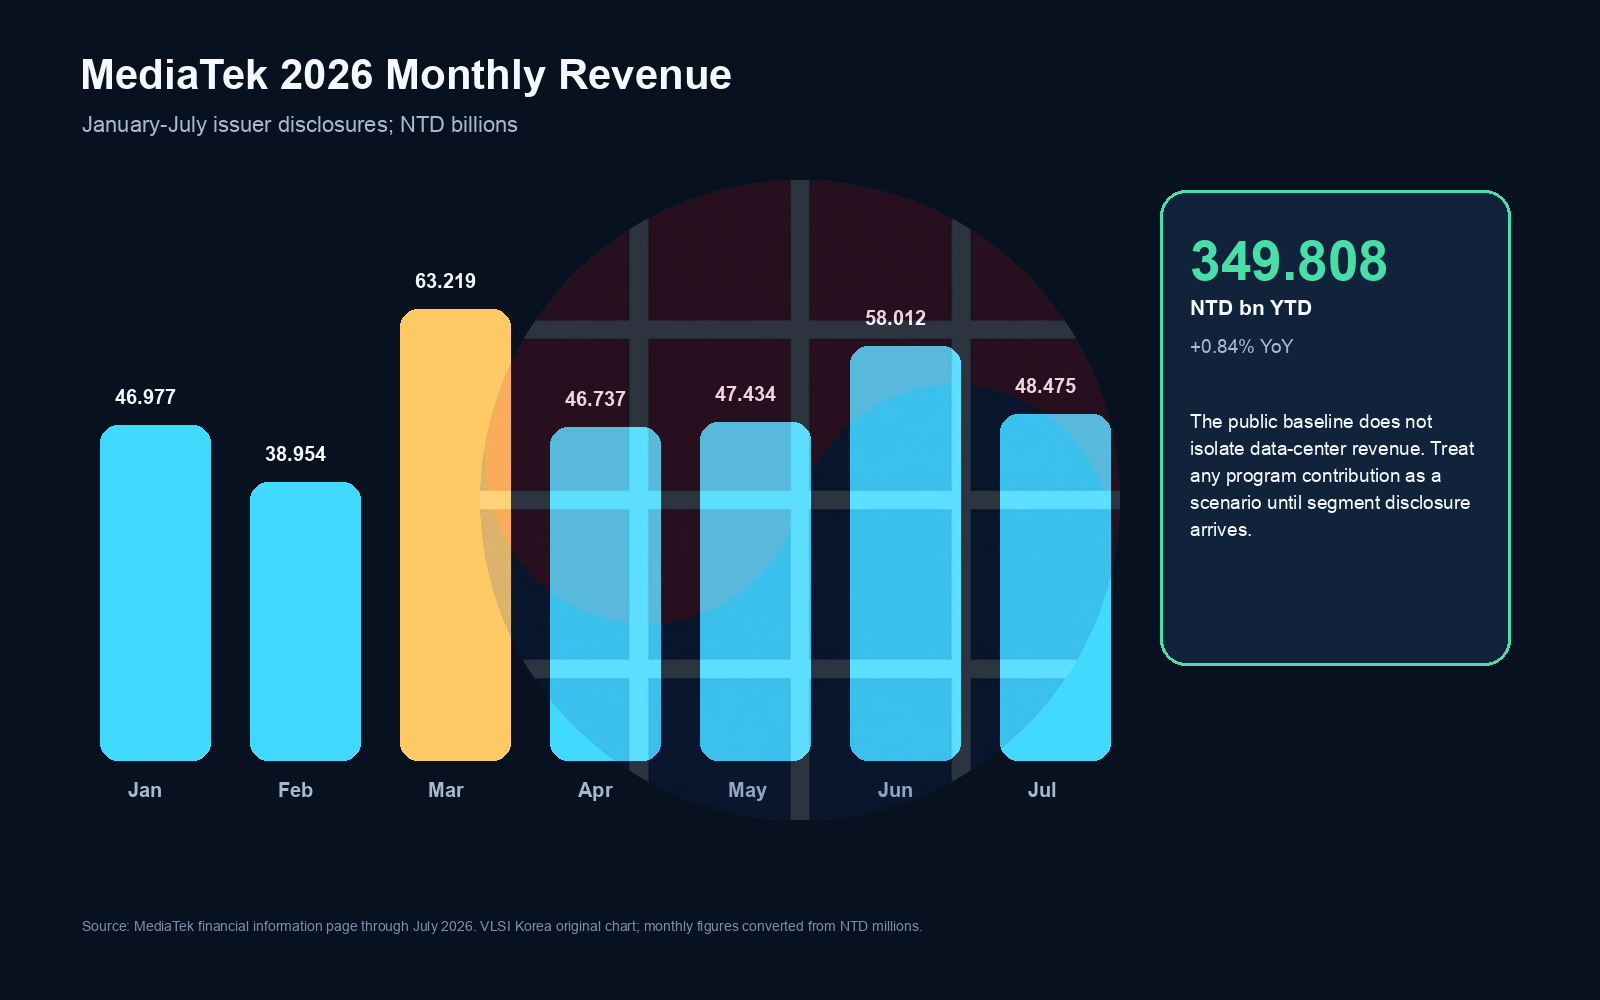
MediaTek의 출발점은 다르다. Monthly revenue page는 2026년 1-7월 누적 NTD349.808 billion을 보고했다. 2025년 같은 기간 NTD346.901 billion보다 0.84% 높다. 1월부터 7월까지 monthly revenue는 NTD46.977 billion, NTD38.954 billion, NTD63.219 billion, NTD46.737 billion, NTD47.434 billion, NTD58.012 billion, NTD48.475 billion이다. 이 숫자는 company-wide revenue이고 data-center segment series가 아니다.
MediaTek의 Q1 2026 earnings release는 margin과 cash context를 제공한다. Revenue NTD149.2 billion, gross margin 46.3%, operating expenses NTD46.2 billion이었다. R&D는 NTD38.345 billion으로 revenue의 25.7%였다. Operating income은 NTD22.891 billion, operating margin은 15.3%, net income은 NTD24.376 billion이었다. Cash와 current financial assets는 NTD194.779 billion이었다. Inventory는 NTD85.470 billion, 87 days였고 quarterly operating cash flow는 negative NTD17.657 billion이었다.
이 수치는 새 program의 stress나 success를 증명하지 않는다. 다만 revenue, gross margin, engineering expense, inventory, cash를 각각 model해야 하는 이유를 보여준다. Custom-XPU program은 reported revenue를 늘리면서도 design work, mask, package qualification, inventory, long-lead capacity, customer support 때문에 cash를 먼저 사용할 수 있다. Convertible은 그 working interval을 finance할 수 있지만 interval 자체를 없애지는 못한다.
2. Thesis는 compute die 하나가 아니라 attach economics에 있다
Custom silicon의 일반적 설명은 substitution에 집중한다. Cloud customer가 merchant accelerator stack 일부를 internally specified XPU로 대체한다는 이야기다. 그러나 이 framing은 불완전하다. Custom compute die에도 memory, die-to-die link, scale-up connectivity, I/O, packaging, board, power delivery, cooling, system software, validation, support가 필요하다. 따라서 economic contest는 arithmetic logic의 owner가 누구인지에 그치지 않는다. 어떤 interface가 나머지 bill of materials를 끌어오는지, 누가 complete system qualification의 대가를 받는지가 중요하다.
NVIDIA의 2025년 5월 NVLink Fusion release는 MediaTek, Marvell, Alchip, Astera Labs, Synopsys, Cadence를 semi-custom ecosystem에 배치했다. NVIDIA는 fifth-generation NVLink가 GPU당 1.8 TB/s의 bandwidth를 제공하고 자사 비교 기준으로 PCIe 5.0의 14배라고 설명했다. 이는 특정 boundary와 generation에 대한 issuer claim이지 모든 system workload의 performance result가 아니다. XPU program이 실제로 interface를 qualify하고 volume shipment에 들어가야 economic evidence가 된다.
2026년 8월 transaction은 공개된 attachment map을 넓힌다. Joint release는 prebuilt, prequalified, system-prevalidated NVLink Fusion element, chiplet approach, NVLink-C2C, NVHBM, advanced packaging, SerDes, I/O, rack integration을 열거한다. 각각은 possible profit pool인 동시에 possible failure boundary다. Prequalified block은 development time을 줄일 수 있지만 final customer design은 workload, memory capacity와 bandwidth, power, thermal, yield, firmware, networking, reliability, rack operations를 다시 맞춰야 한다.
NVIDIA의 NVHBM material은 HBM4e 대비 stack당 bandwidth 최대 30% 증가, PHY와 supporting-logic area 최대 67% 감소, HBM power 최대 15% 감소, XPU당 end-to-end performance 최대 30% 개선을 주장한다. Public summary에 workload와 implementation condition이 충분히 명시되지 않은 vendor claim이므로 realized customer outcome처럼 입력하면 안 된다. 분석적으로 중요한 점은 NVIDIA가 neighboring GPU만 판매하는 것이 아니라 memory-interface IP와 validation까지 custom-XPU attachment surface에 포함하려 한다는 것이다.
MediaTek의 Computex 2026 disclosure는 complementary full-stack role을 설명한다. Custom ASIC와 XPU design, 2.5D와 3.5D packaging, high-speed interconnect, rack integration, CPO work가 포함된다. MicroLED active optical cable power를 50% 줄인다는 설명 역시 audited fleet result가 아니라 company claim이다. 두 회사 disclosure를 합치면 NVIDIA는 fabric, memory interface, software ecosystem, system qualification을, MediaTek은 customer-specific silicon과 integration capability를 제공하는 division of labor가 나타난다.
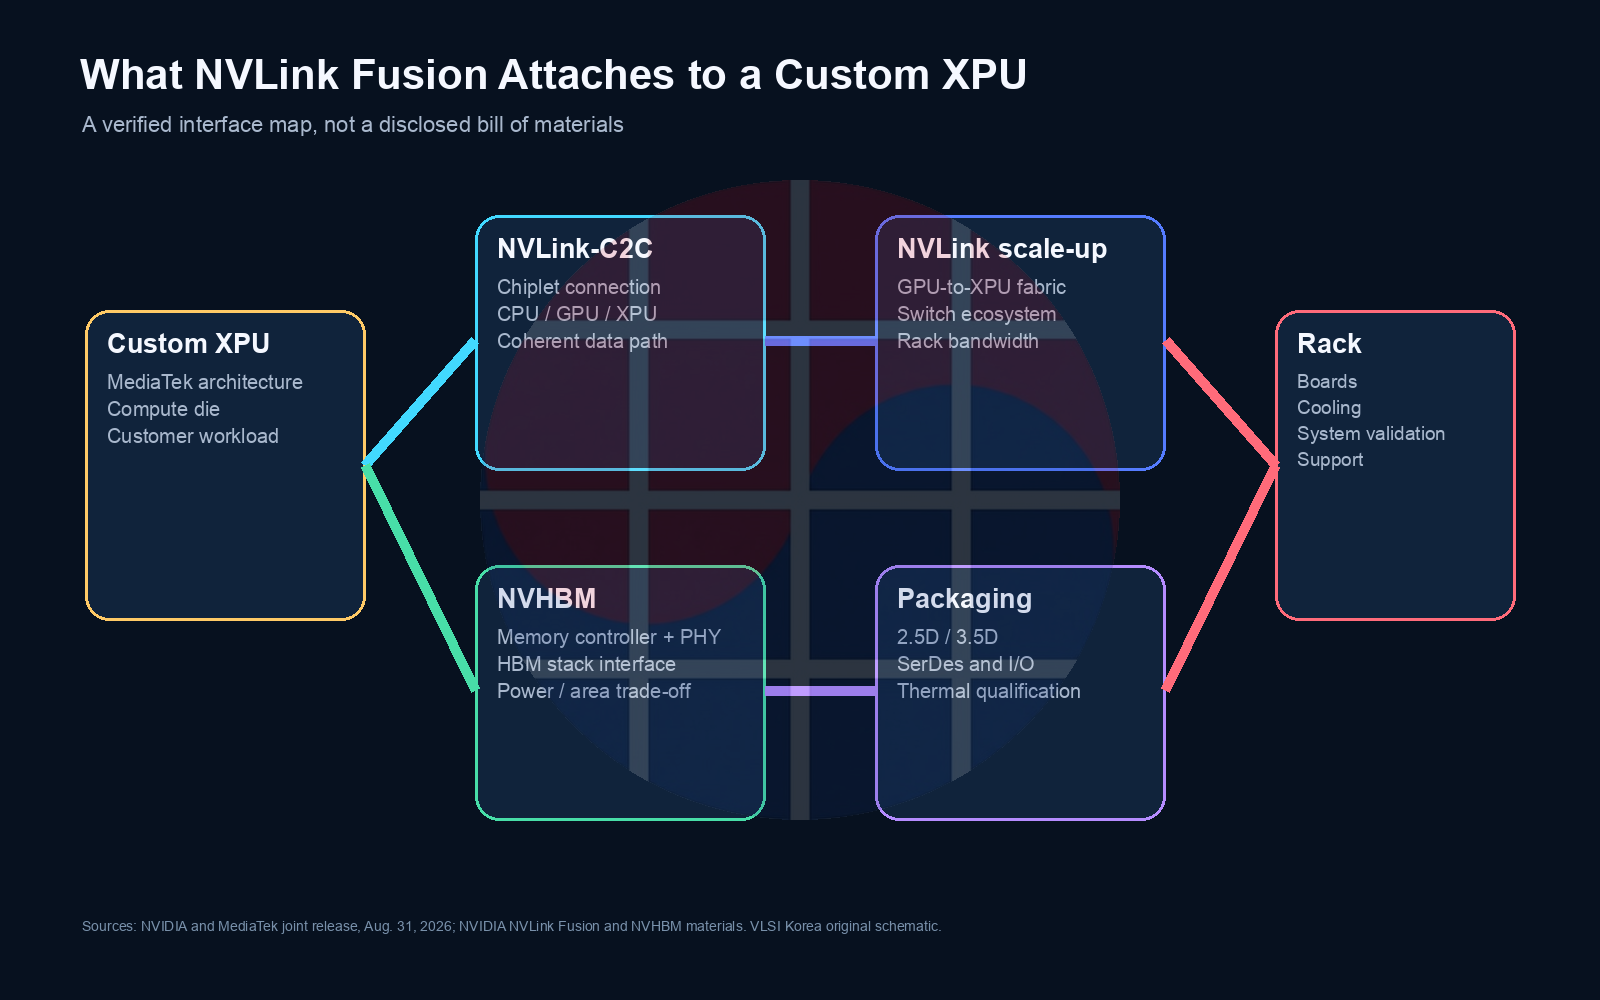
Collaboration에는 적어도 하나의 shipped precedent가 있다. MediaTek의 2025년 10월 DGX Spark release는 NVIDIA와 공동 설계한 GB10 Superchip이 20-core Arm CPU와 NVIDIA GPU를 결합했다고 설명한다. System은 up to one petaflop AI performance와 128 GB unified memory를 제공하며, company claim 기준 up to 200 billion parameter model, paired system에서는 up to 405 billion parameter model을 다룬다. Product claim이라는 한계는 있지만 shipped collaboration은 partner logo보다 강한 evidence다. Architectural coordination이 commercial system까지 도달할 수 있음을 보여준다.
그러나 precedent는 scale proof가 아니다. DGX Spark는 hyperscale-XPU volume, segment margin, NVLink Fusion attachment economics를 공개하지 않는다. 줄여주는 것은 한 종류의 execution risk다. NVIDIA와 MediaTek이 복잡한 compute product를 이미 공동 설계했다는 점이다. 새로운 thesis에는 여전히 customer-specific tapeout, production qualification, repeat order가 필요하다.
3. Financing이 recurring cash가 되려면 여섯 gate를 통과해야 한다
가장 강한 skeptical interpretation은 circular financing이다. NVIDIA가 ecosystem partner에게 capital을 제공하고, partner가 NVIDIA interface를 중심으로 product를 만들며, independent customer가 지불하기 전에 activity를 demand처럼 설명할 위험이다. Reuters report는 이 transaction을 AI circular-financing debate 안에 배치한다. Bloomberg, TechCrunch, Dow Jones Newswires도 거래 규모와 custom-silicon context를 independent하게 확인한다. Cross-check는 deal이 존재한다는 사실을 강화하지만 ultimate customer cash flow가 independent한지는 답하지 못한다.
Category error를 피하기 위해 이 글은 여섯 단계 Bond-to-Revenue Evidence Ladder를 사용한다. Rung 1은 funded convertible이다. Definitive terms, cash transfer, use of proceeds, accounting, conversion mechanics를 확인한다. Rung 2는 named commercial program이다. Customer, workload, architecture, delivery responsibility, economic owner가 필요하다. Rung 3은 tapeout이다. Design freeze, mask, wafer, dated production path가 필요하다. Rung 4는 qualified package다. Yield, HBM interface, thermal, SerDes, reliability가 통과해야 한다. Rung 5는 accepted rack이다. Networking, software, power, cooling, customer acceptance가 맞아야 한다. Rung 6는 recurring cash다. Repeated volume shipment가 recognized되고 partner finance가 아닌 customer에게서 collected돼야 한다.
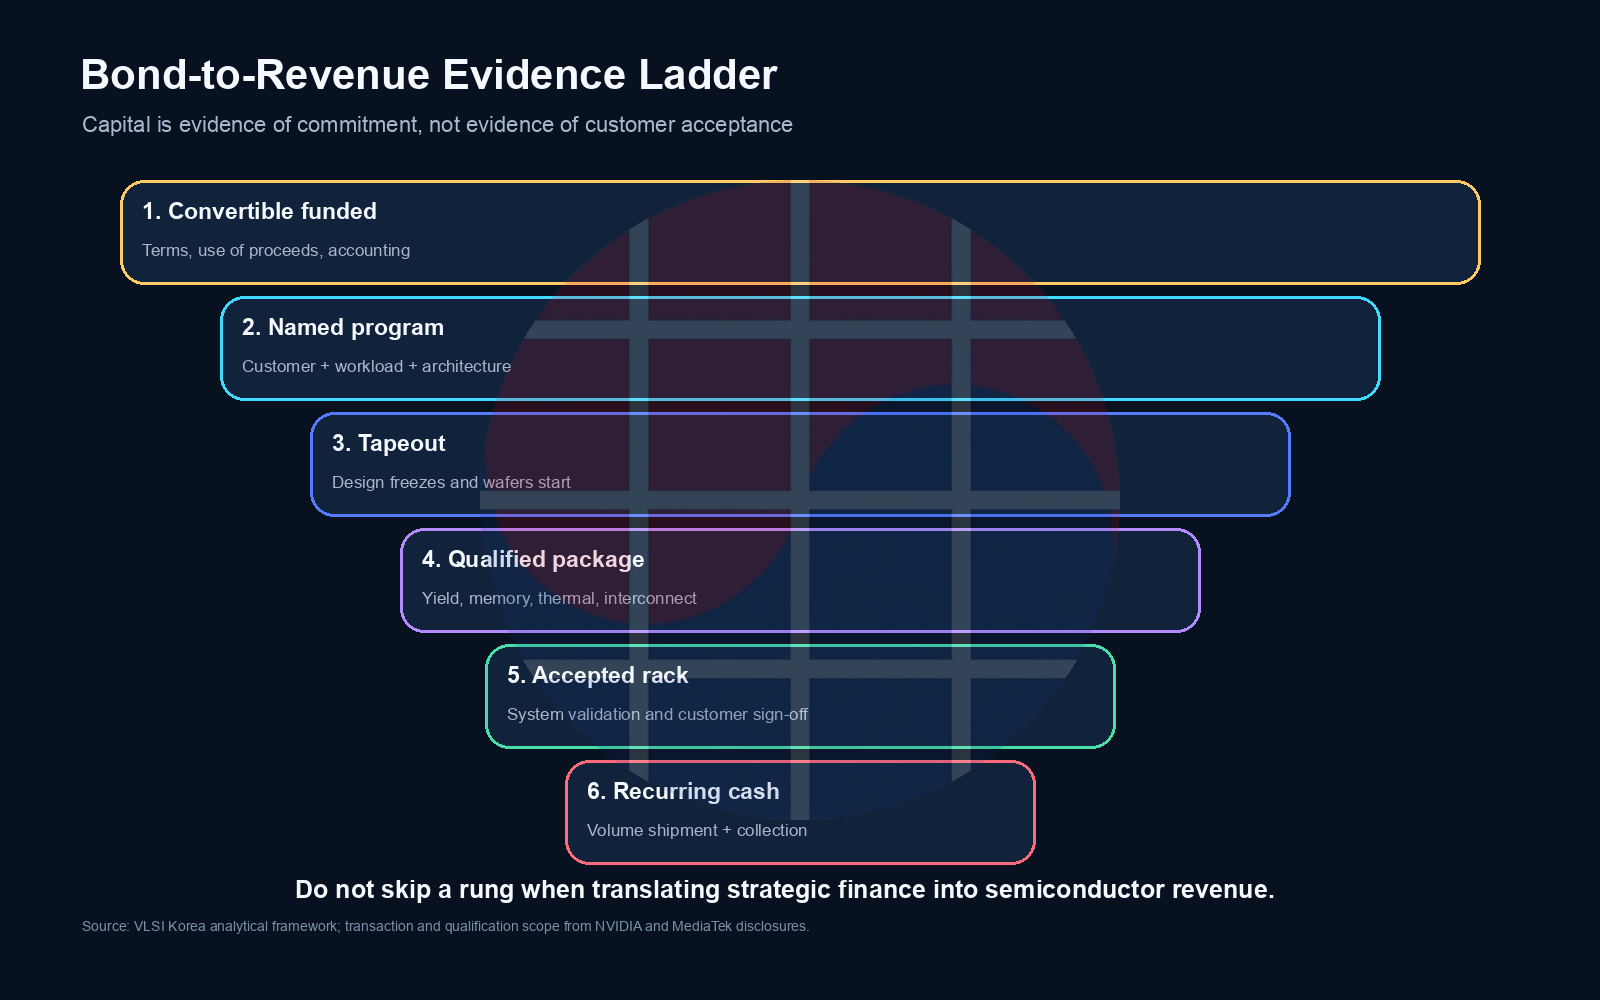
Boundary condition: US$3.5 billion face amount를 semiconductor revenue, backlog, order, data-center TAM에 더하면 안 된다. Contract와 accounting disclosure가 달리 보여주기 전에는 financing instrument다.
Ladder는 bullish case도 약한 논리에서 보호한다. Customer revenue가 공개되기 전에도 ecosystem investment는 rational할 수 있다. Engineering을 앞당기고, packaging 또는 memory capacity를 예약하고, interface를 표준화하고, partner attention을 확보하고, schedule risk를 줄이는 option이 될 수 있다. 모두 real strategic option이다. 다만 option과 execution capacity로 불러야지 completed demand로 부르면 안 된다.
Marvell에서 comparable evidence를 볼 수 있다. 2026년 3월 31일 Marvell release는 NVIDIA가 US$2 billion을 투자했고 두 회사가 Marvell custom XPU와 scale-up networking을 NVIDIA platform에 연결한다고 밝혔다. 반복되는 pattern은 financing plus attachment stack이다. 다음 분석은 investment dollars를 market share로 세는 것이 아니라 어떤 partner가 named program, tapeout, qualified system, cash를 만드는지 비교해야 한다.
Convertible form은 별도 risk를 만든다. Bond는 MediaTek control을 유지하면서 NVIDIA에 upside exposure를 줄 수 있지만 public release는 conversion economics를 밝히지 않았다. Dilution, coupon, maturity, settlement method, covenant, strategic right는 value distribution을 바꿀 수 있다. Commercial outcome이 같아도 조건에 따라 두 회사 shareholder에게 돌아가는 결과가 다르다. Filing이 terms를 제공하기 전 implied ownership percentage나 return을 계산하면 speculation이다.
4. NVLink와 open interface는 같은 boundary에서만 경쟁하지 않는다
약한 comparison은 NVLink, UALink, UCIe, PCIe를 bandwidth table 하나에 넣고 winner를 선언한다. 하지만 interface는 일부 overlap하면서 서로 다른 system boundary를 다룬다. NVLink Fusion은 NVIDIA 중심 scale-up과 chiplet ecosystem을 포괄한다. UALink는 open scale-up fabric이다. UCIe는 die-to-die chiplet connectivity에 집중한다. PCIe는 general-purpose I/O foundation이다. 하나의 architecture가 여러 interface를 함께 사용할 수 있으므로 한 layer의 adoption이 다른 layer를 자동으로 제거하지 않는다.
UALink Consortium의 2026년 4월 release는 UALink 2.0이 open scale-up ecosystem 안에서 in-network compute, manageability, chiplet use를 지원한다고 설명한다. NVLink Fusion에 대한 investment risk는 UALink가 특정 bandwidth number를 제시한다는 데 있지 않다. Silicon, switch, cable, software, compliance, production system이 충분히 interoperable해져 customer가 schedule 또는 reliability를 잃지 않고 non-NVIDIA scale-up path를 qualify하는 데 있다.
UCIe Consortium의 UCIe 3.0 announcement는 chiplet interconnection에 48 GT/s와 64 GT/s data rate, manageability feature를 추가했다. Package boundary와 rack boundary는 같지 않으므로 UCIe는 higher-level scale-up fabric과 coexist할 수 있다. MediaTek에는 open die-to-die layer가 design choice를 넓힐 수 있고, NVIDIA에는 그 위 complete system qualification을 장악하는 것이 attachment를 지키는 수단이 될 수 있다.
PCI Express 7.0 specification page는 128 GT/s와 x16 configuration 기준 up to 512 GB/s bidirectional bandwidth를 제시한다. PCIe의 broad compatibility, switching, I/O role은 여전히 중요하다. NVIDIA의 1.8 TB/s comparison은 scale-up performance distinction을 보여주려는 것이지만 raw bandwidth 외에도 protocol semantics, topology, latency, coherency, software, power, workload behavior가 중요하다.
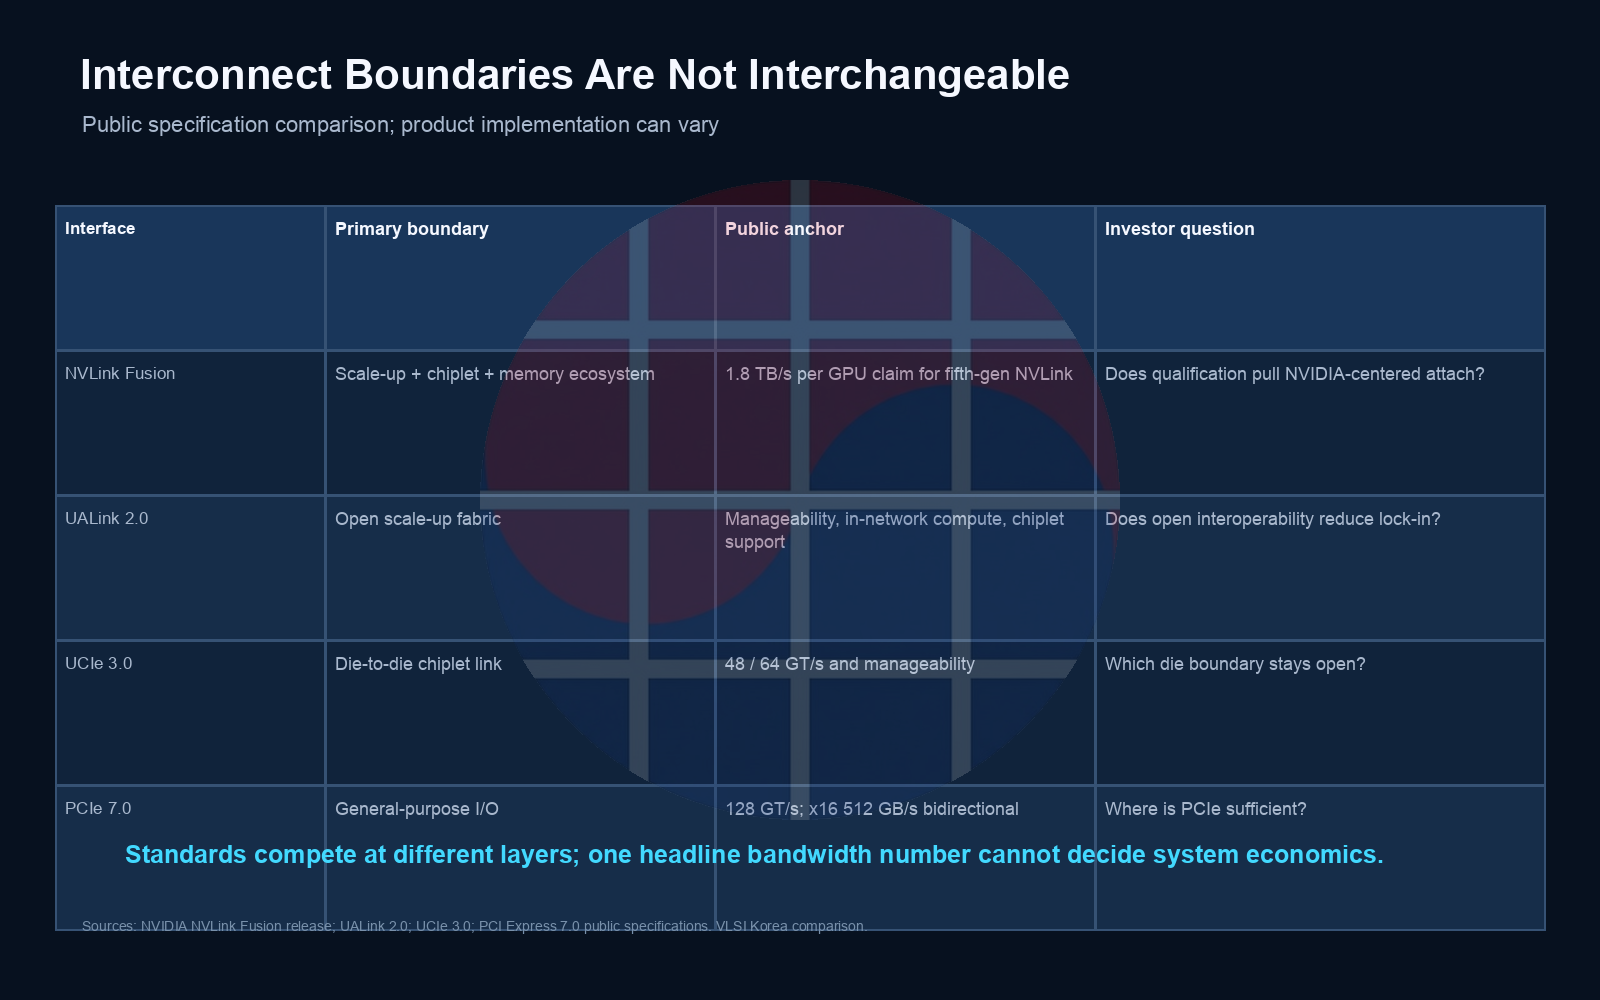
따라서 정확한 variant perception은 “NVLink wins” 또는 “open standards win”이 아니다. Profit pool은 qualification friction에 달려 있다. NVIDIA와 MediaTek의 prevalidated block이 customer schedule을 줄이면 lower layer가 open이어도 NVLink attachment가 value를 얻을 수 있다. 반대로 UALink와 UCIe ecosystem이 broader supplier choice와 함께 comparable system validation에 도달하면 customer는 attachment share를 낮출 수 있다. 결정 변수는 ideology가 아니라 time-to-qualified-rack, workload performance, reliability, supply assurance, total cost다.
Standards checkpoint를 investment thesis에 넣는 이유가 여기 있다. Press release가 consortium을 열거하고 specification이 complete해도 production interoperability는 immature할 수 있다. Evidence는 compliant silicon, switch, cable과 connector ecosystem, software support, compliance event, reference system, independently announced deployment 순서로 발전해야 한다. Convertible에 적용한 ladder discipline을 open standard에도 똑같이 적용해야 한다.
5. Financial transmission: volume, price, mix, margin, capex, cash
Economic bridge는 financed dollars가 아니라 qualified XPU units에서 시작한다. 정해진 기간 compute revenue는 qualified units와 realized compute ASP의 곱이다. Attached revenue는 program에 economically linked된 product와 service를 더한다. Interface IP, chiplet, memory controller와 PHY, packaging content, SerDes 또는 I/O, switch, optics, board, rack integration, software, support가 포함된다. Value 일부는 NVIDIA와 MediaTek에, 많은 부분은 third-party foundry, HBM, OSAT, substrate, networking, optical, power supplier에 귀속될 수 있다.
Volume은 named-program count, program당 units, yield, customer acceptance, ramp shape에 달려 있다. Price는 die complexity, packaging, memory interface, service scope, commercial terms에 달려 있다. Mix는 qualified XPU 중 NVLink-connected GPU, NVHBM, NVIDIA IP, broader NVIDIA rack component를 사용하는 비중이다. Margin은 wafer, HBM, packaging, board, test, warranty, software, field support를 누가 부담하는지에 달려 있다. Capex와 working capital은 mask, tool, inventory, capacity reservation, payment terms, collection lag에 달려 있다.
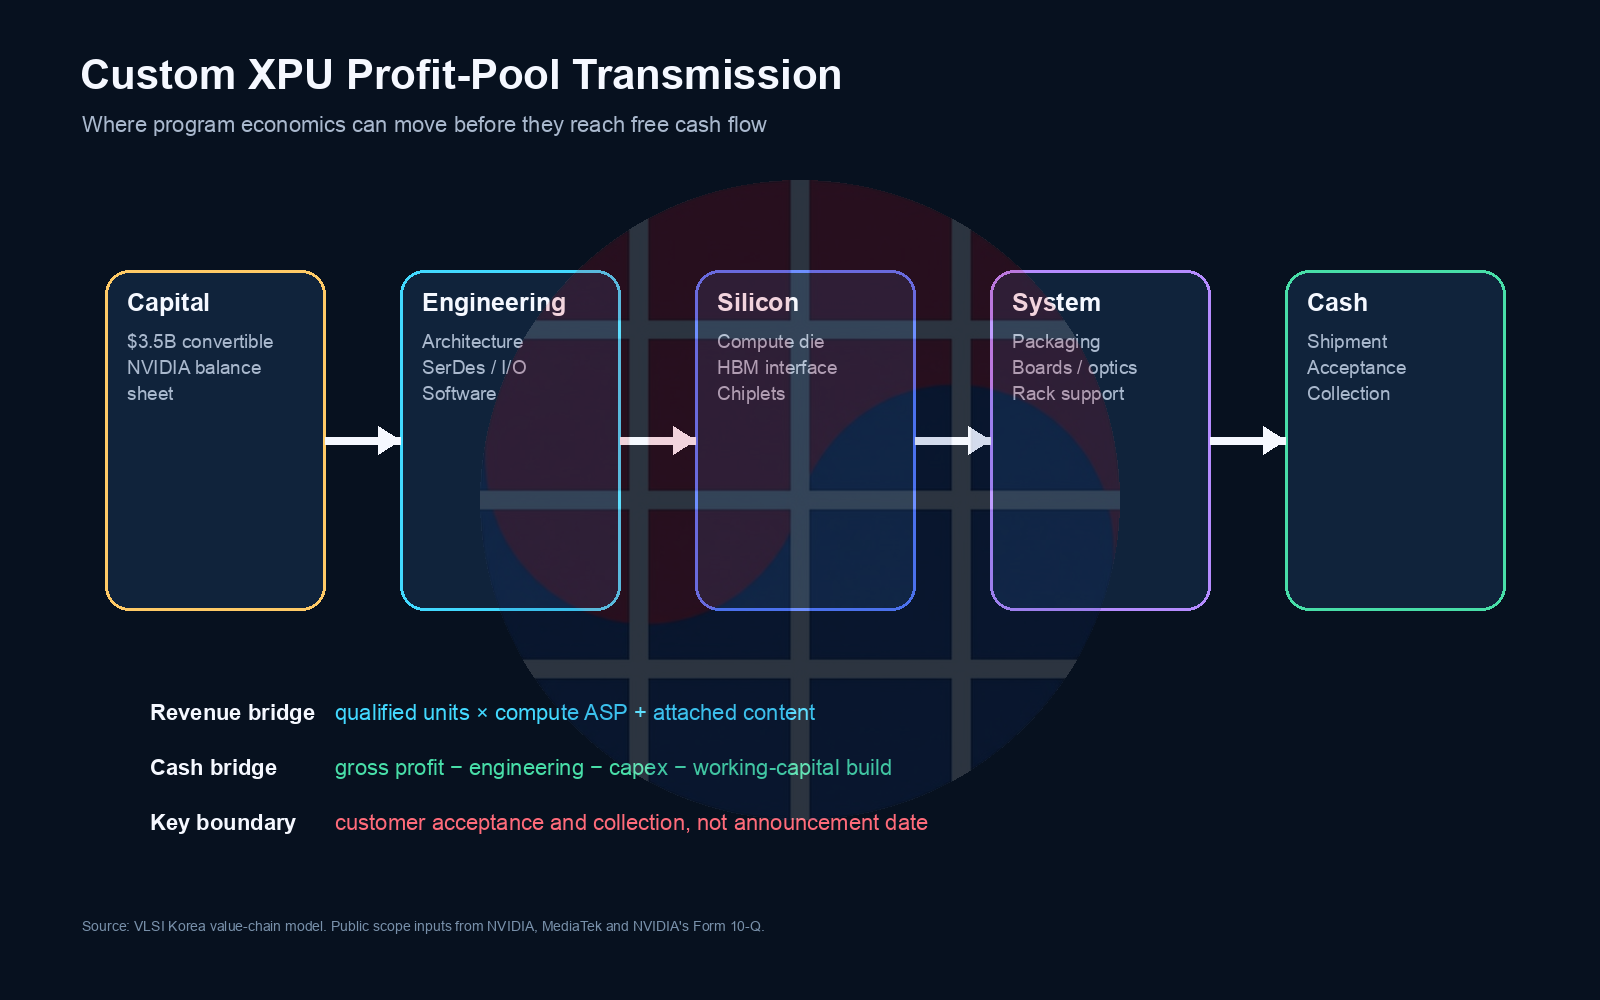
Practical revenue equation은 qualified units × compute ASP × [1 + connected mix × attach-value ratio]다. Accounting guidance가 아니라 simplification이다. Unit volume, compute price, attachment를 분리해 한 가지 흔한 오류를 막는다. Practical cash proxy는 gross profit에서 incremental engineering, program capex, working-capital build를 빼는 것이다. Gross-margin-positive program도 qualification과 ramp 동안 cash를 사용할 수 있다는 두 번째 오류를 막는다.
NVIDIA filing은 gross-margin cost component에 wafer fabrication, assembly, testing, packaging, board, memory를 포함한다. 이 list는 attach thesis가 NVIDIA와 MediaTek 밖으로 전파되는 이유를 보여준다. Production에 들어간 custom XPU는 leading-edge logic wafer, HBM stack, interposer, advanced-package capacity, substrate, SerDes, switch, retimer, optical link, power stage, connector, cooling을 끌 수 있다. Revenue와 risk allocation은 contract ownership에 달려 있지만 public release는 allocation을 공개하지 않았다.
MediaTek Q1 consolidated gross margin 46.3%는 baseline으로 유용하지만 data-center segment margin이 아니다. Mobile, connectivity, consumer, edge, data-center product는 wafer, packaging, support, pricing이 다르다. 이 글의 base scenario는 46.3%를 transparent anchor로만 사용한다. Downside와 upside margin은 sensitivity assumption이다. Custom-XPU program이 이미 어느 margin을 벌고 있다는 주장을 하지 않는다.
Working capital도 똑같이 중요하다. MediaTek은 Q1에 87 inventory days와 negative quarterly operating cash flow를 보고했고 높은 R&D load를 유지했다. New program은 customer acceptance 전에 inventory와 engineering을 요구할 수 있다. Convertible은 그 interval을 bridge할 수 있다. 어떤 expenditure가 incremental인지, customer가 어떤 비용을 reimburse하는지, volume commitment가 non-cancellable인지, receivable이 얼마나 빨리 cash가 되는지를 disclosure가 보여줄수록 financing thesis의 quality가 높아진다.
6. 모든 assumption을 드러낸 reproducible scenario
Public release가 program volume과 ASP를 공개하지 않았으므로 scenario는 index를 사용한다. Base qualified units를 100, base compute ASP를 100으로 normalize한다. Downside는 unit index 50, ASP index 90이고 upside는 160과 105다. NVLink-connected mix는 20%, 40%, 60%를 가정한다. Attached value는 compute value의 10%, 15%, 20%를 가정한다. Base gross-margin anchor 46.3%를 제외하면 모두 analytical assumption이지 company guidance가 아니다.
계산은 재현할 수 있다. Downside revenue index = 50 × 90 / 100 × [1 + 20% × 10%] = 45.9다. Base revenue index = 100 × 100 / 100 × [1 + 40% × 15%] = 106.0이다. Upside revenue index = 160 × 105 / 100 × [1 + 60% × 20%] = 188.16이고 188.2로 반올림한다. Gross margin 40.0%, 46.3%, 50.0%를 적용하면 gross-profit index는 18.4, 49.1, 94.1이다.
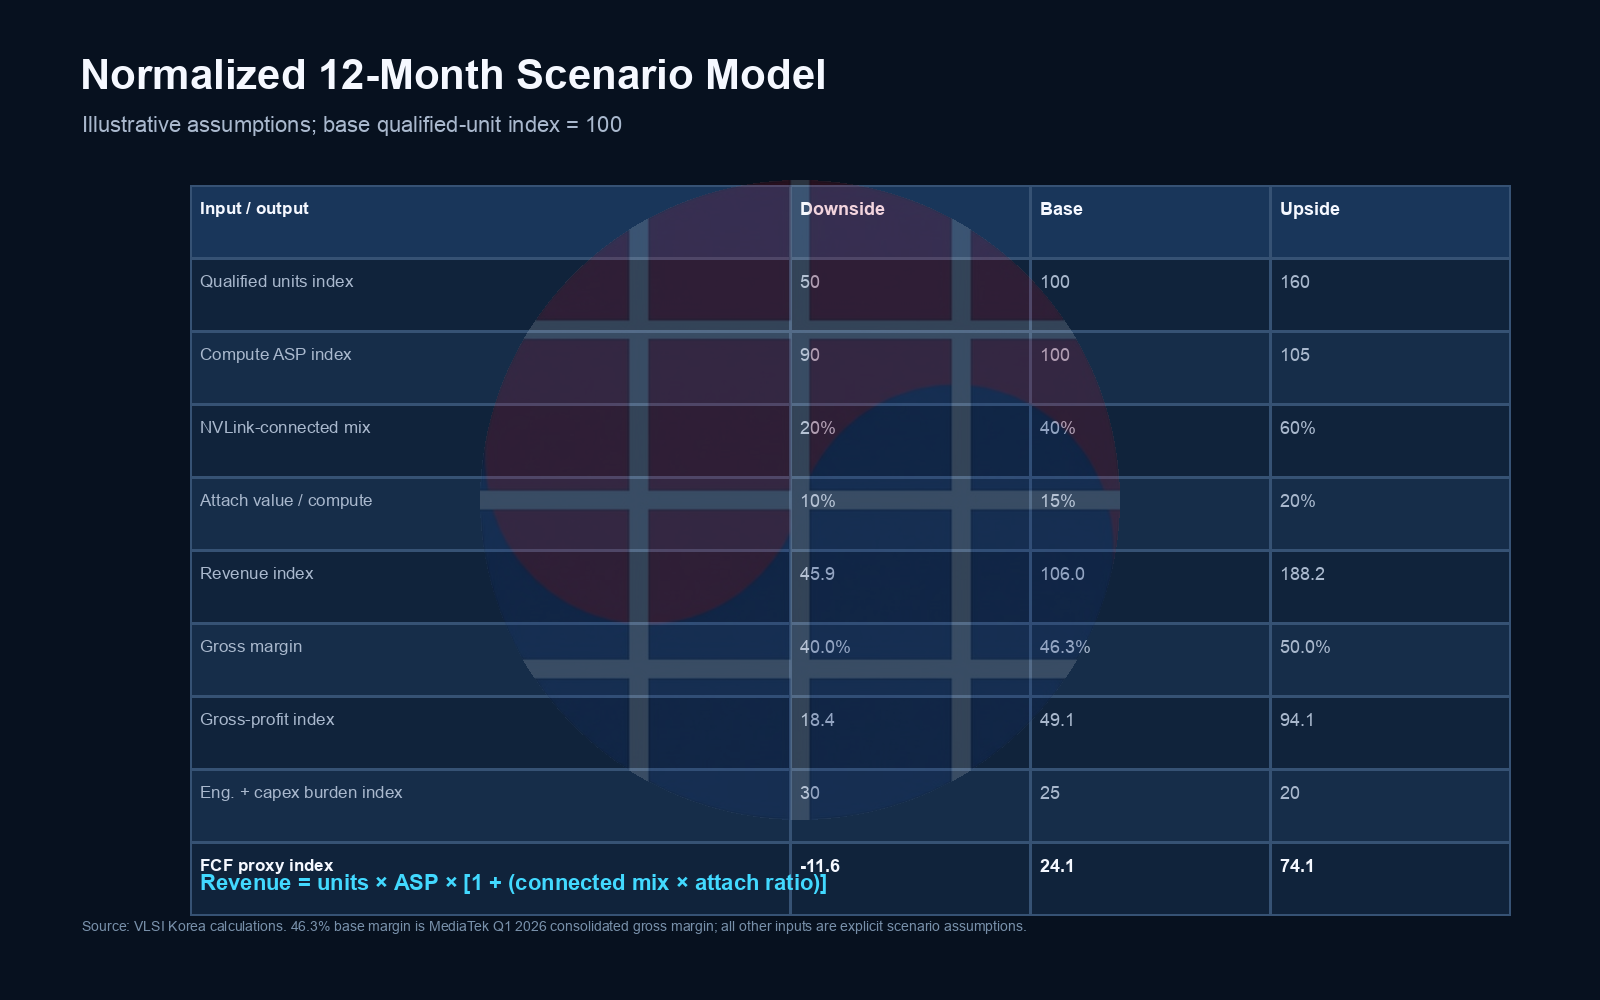
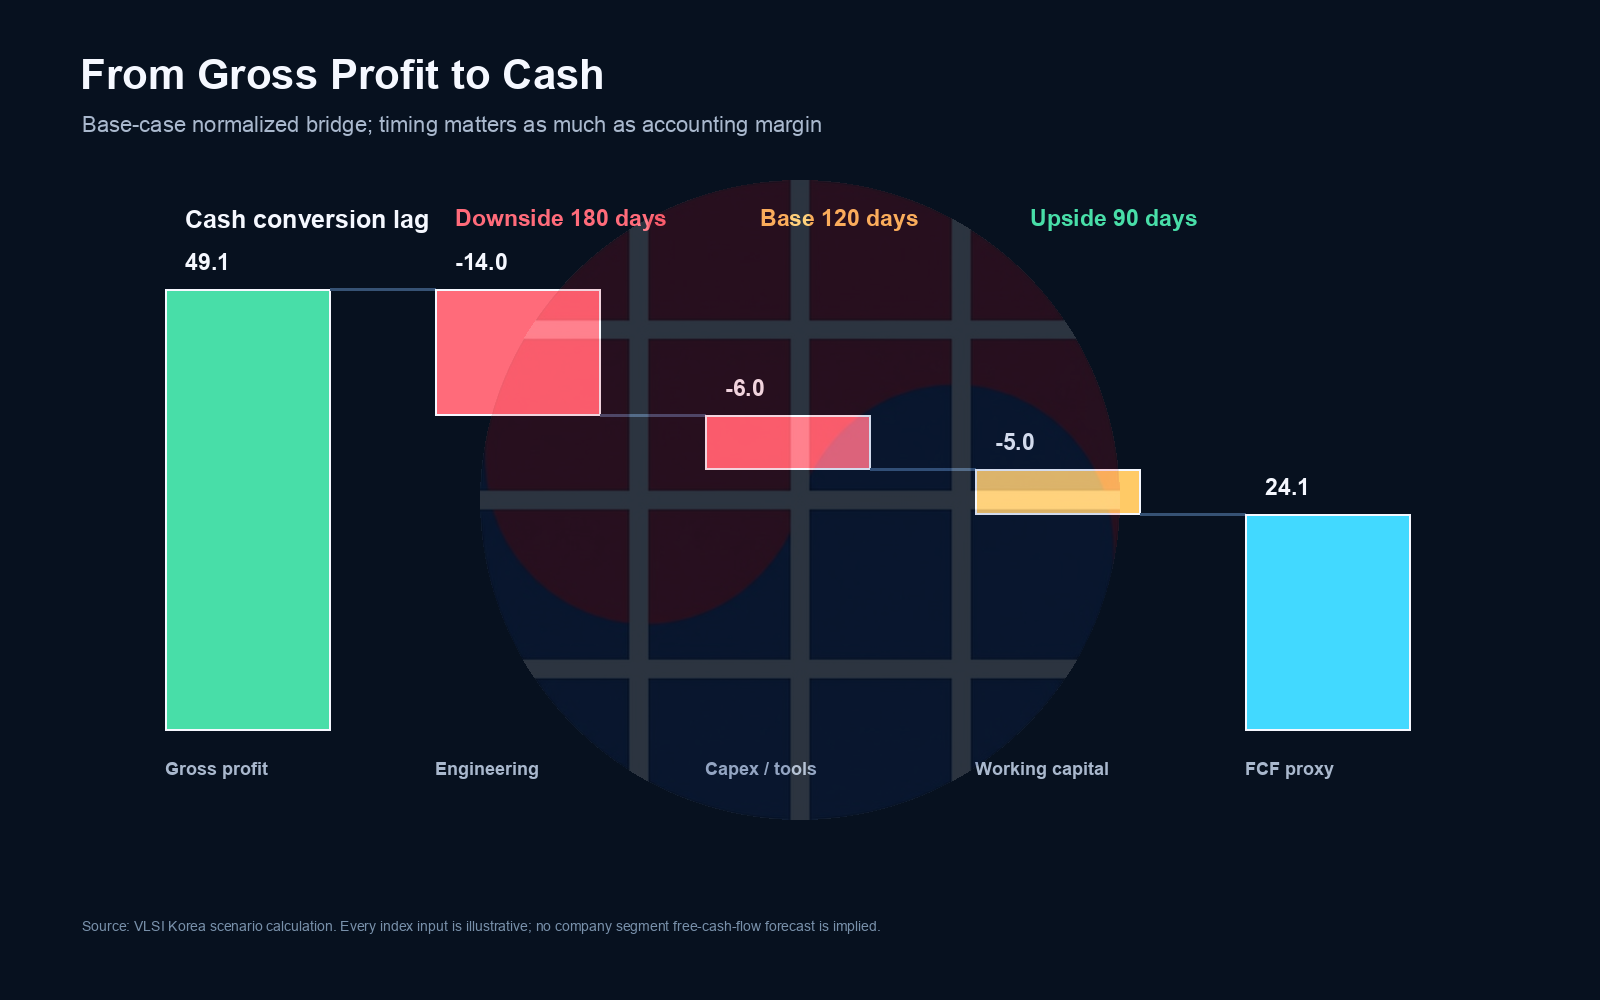
다음으로 engineering-and-capex burden index 30, 25, 20을 뺀다. Free-cash-flow proxy는 downside negative 11.6, base positive 24.1, upside positive 74.1이 된다. Company free cash flow forecast가 아니다. Mechanism을 보여주는 sensitivity다. Low volume과 weak attachment는 largely fixed engineering burden을 흡수하지 못할 수 있고, 더 높은 qualified volume과 attachment는 operating leverage를 만들 수 있다.
Scenario는 illustrative cash-conversion lag도 180 days, 120 days, 90 days로 둔다. Revenue recognition과 collection이 같은 시점일 필요는 없다. Package inventory, system acceptance, customer payment term, support obligation이 interval을 늘릴 수 있다. Acceptance와 collection clock 없이 revenue만 보여주는 model은 financing thesis에 불완전하다.
Evidence가 나오면 reader가 모든 input을 교체할 수 있다. Named customer와 qualified units가 volume을 update한다. Contract disclosure와 product mix가 ASP와 attachment를 update한다. Segment reporting 또는 management commentary가 gross margin을 update한다. R&D, mask, packaging, tool, capacity commitment가 burden을 update한다. Inventory days, receivable, acceptance, payment term이 cash lag를 update한다. Model은 decimal을 더할 때가 아니라 assumption을 fact로 바꿀 때 더 informative해진다.
각 case에는 dated falsifier가 있어야 한다. Multiple named customer가 qualified production system을 공개하고 attachment가 넓어지며 MediaTek이 disproportionate inventory build 없이 margin과 cash conversion을 보여주면 downside는 지나치게 낮다. Program slip, open fabric의 attach content 축소, support cost 상승, transaction anniversary까지 independent customer cash evidence 부재가 나타나면 upside는 지나치게 높다. Base는 prediction이 아니다. Fact에 따라 input이 움직여야 하는 transparent midpoint다.
Scenario rule: Company의 US$2 billion data-center revenue guide와 normalized model을 둘 다 observed custom-XPU revenue인 것처럼 섞지 않는다. Guide는 business category에 대한 management claim이고 model은 한 transmission mechanism의 analytical sensitivity다.
7. 다섯 catalyst와 다섯 risk를 같은 event로 검증한다
Catalyst 1, 2026-10-30: MediaTek의 expected Q3 reporting window에서 definitive bond terms, use of proceeds, named program, qualification stage, updated data-center bridge를 찾는다. Issuer가 calendar를 공개하기 전까지 date는 monitoring assumption이다. Paired risk는 customer, unit, margin, cash evidence 대신 general strategic language만 반복되는 것이다.
Catalyst 2, 2026-11-19: NVIDIA의 expected Q3 filing window에서 strategic-investment classification, cash-flow treatment, related commitment, adoption evidence를 확인한다. Paired risk는 bond가 separable commercial return 없이 더 큰 investment program에 묻히거나 terms가 한쪽에 disproportionate risk를 넘기는 것이다.
Catalyst 3, 2027-01-31: MediaTek full-year disclosure를 public data-center narrative와 비교한다. MediaTek corporate blog는 2026 AI data-center ASIC revenue guide를 US$2 billion으로 제시했다. 더 이른 corporate update에는 다른 timing과 scale frame이 알려져 있다. 올바른 방법은 publication date와 scope를 보존하는 것이지 두 숫자를 합치는 것이 아니다. Paired risk는 reconcile 가능한 segment bridge가 없거나 data-center revenue가 늘어도 inventory와 cash conversion이 악화되는 것이다.
Catalyst 4, 2027-04-07: UALink 2.0 specification release 1년 뒤 ecosystem을 평가한다. Compliant silicon, switch와 cable ecosystem, manageability, software support, reference system, interoperability result, production customer use를 본다. NVLink attach thesis의 paired risk는 open path가 broader vendor choice와 comparable qualification에 도달하는 것이다.
Catalyst 5, 2027-08-31: Transaction anniversary에 named program, tapeout, qualified package, accepted rack, repeat order, collected cash를 요구한다. Paired risk는 financing과 partnership activity는 보이지만 independent customer conversion은 계속 보이지 않는 것이다.
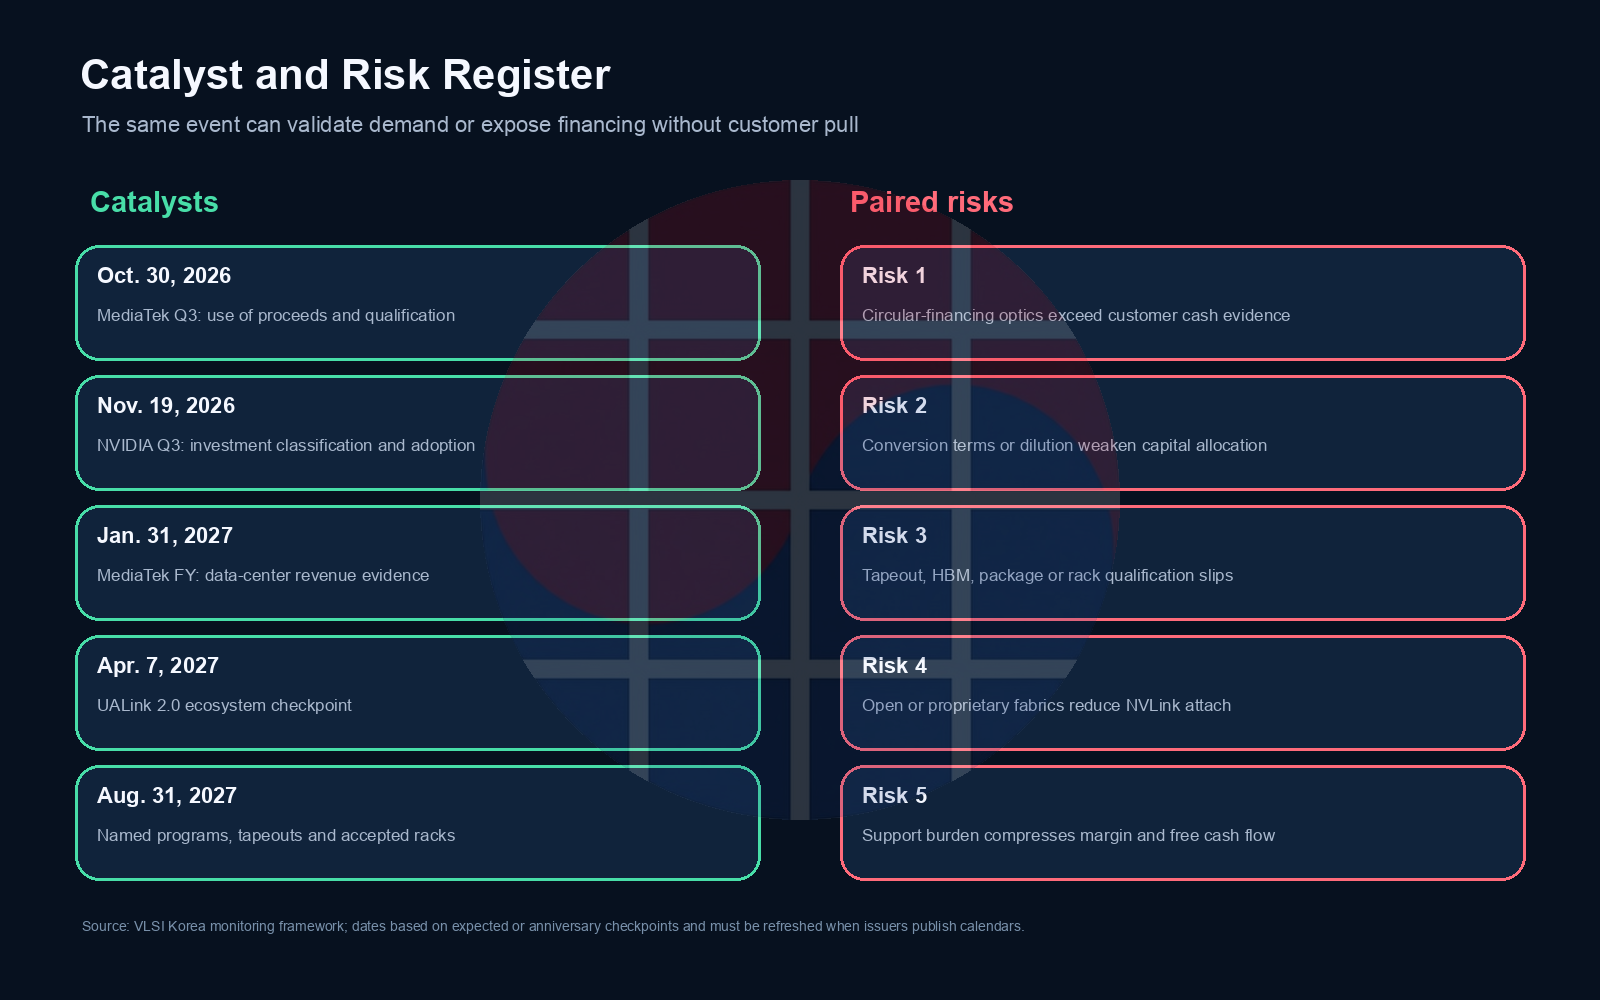
Register가 symmetric한 데는 이유가 있다. Better disclosure는 thesis를 validate하거나 가장 약한 link를 드러낼 수 있다. Headline revenue가 높아도 low margin, high inventory, negative cash conversion, large support obligation이 동반되면 자동으로 좋은 signal이 아니다. 한 program이 delayed돼도 다른 customer가 tapeout하고 qualification stack이 reusable해지면 자동으로 thesis breaker가 아니다. Monitor의 unit은 press-release sentiment가 아니라 program과 attachment다.
네 가지 explicit thesis breaker가 있다. 첫째, MediaTek이 2027 checkpoint까지 material design win 또는 revenue conversion을 공개하지 않는다. 둘째, UALink production deployment가 NVLink Fusion 없이 comparable rack qualification과 customer breadth를 달성한다. 셋째, packaging, HBM, support cost가 attached revenue를 흡수해 partner gross margin 또는 free cash flow가 악화된다. 넷째, independent customer disclosure가 convertible이 incremental NVLink-connected program 없이 general liquidity를 finance했다고 보여준다.
8. Korea lens: supply-chain evidence는 어디에서 나타나야 하나
Samsung Electronics와 SK hynix에 필요한 demand signal은 bond amount가 아니다. Qualified package 수, HBM generation과 package당 capacity, memory-interface ownership, yield, customer acceptance, ramp quarter다. NVHBM은 memory boundary에서 NVIDIA 영향력을 넓힐 수 있지만 HBM revenue는 stack, tested interface, qualified package, system acceptance가 있어야 한다. Korean memory question은 attachment가 qualified HBM content를 늘리는지, 아니면 interface control만 바꾸는지다.
Samsung Foundry와 logic manufacturing team에는 design release, process node, die size, yield learning, wafer start, repeat program이 custom-XPU value를 결정한다. Funded architecture는 high-volume wafer를 만들지 않은 채 engineering attention만 예약할 수 있다. Mask activity, tapeout statement, advanced-package capacity, customer ramp evidence를 본다. Prototype wafer start와 production volume curve를 분리해야 한다.
OSAT, substrate, equipment supplier에는 attachment thesis가 더 직접적일 수 있다. Chiplet, HBM, 2.5D 또는 3.5D integration, high-speed I/O는 package complexity를 높인다. Qualified unit당 content를 늘리는 동시에 yield와 schedule risk도 높일 수 있다. Useful metric은 complexity 자체가 아니다. Rework와 test time을 반영한 constrained capacity 단위당 good package shipped and accepted다.
SerDes, networking, optics, power, board, connector, cooling supplier에는 rack boundary가 opportunity를 결정한다. Customer는 MediaTek XPU를 사용하면서 fabric, optical reach, power topology, cooling design을 달리할 수 있다. CPO와 active optical cable claim은 field validation, reliability data, system-level energy measurement가 필요하다. Interface win은 모든 category를 동시에 늘리기보다 copper, optics, retimer, switch, connector 사이에서 spend를 옮길 수 있다.
EDA와 IP company에는 NVIDIA의 prequalified-block strategy가 verified interface IP, model, emulation, SI/PI analysis, thermal analysis, compliance workflow의 value를 높일 수 있다. 더 많은 block이 platform에 bundle되면 merchant opportunity를 좁힐 수도 있다. Evidence는 tool seat, IP royalty, design-service revenue, recurring support를 구분해야 한다. Ecosystem에 이름이 있다는 사실이 모든 EDA 또는 IP vendor의 disclosed contract는 아니다.
Korean corporate strategy team의 decision은 NVIDIA-centered custom silicon, open alternative, 또는 둘 다에 capacity와 product roadmap을 얼마나 align할지다. Portfolio approach는 optionality를 보존할 수 있지만 qualification resource는 finite하다. 올바른 gate는 customer-funded program evidence다. Named architecture, interface choice, package release, rack acceptance, volume schedule이 필요하다. Capital allocation은 generalized custom-silicon TAM이 아니라 이 gate를 따라야 한다.
9. Watch sequence와 final judgment
Announcement date에 관측된 evidence는 US$3.5 billion convertible, broad collaboration scope, prior shipped co-design, NVIDIA strategic-investment capacity, MediaTek revenue와 margin baseline, competing open-interface specification이다. Missing evidence는 bond terms, customer identity, units, ASP, attachment, segment margin, capex, working capital, acceptance schedule이다. 두 list를 분리해야 thesis를 monitoring problem으로 다룰 수 있다.
First reporting window에는 accounting classification과 program-stage language를 기대한다. Full-year reporting에서는 reconcile 가능한 data-center revenue and cash bridge를 요구한다. Open-fabric checkpoint에서는 specification headline이 아니라 system qualification을 비교한다. Transaction anniversary에는 independent customer, tapeout, qualified rack, repeat order, cash conversion을 요구한다. Evidence가 partnership language에서 멈추면 attach thesis는 ladder를 건너지 못한 것이다.
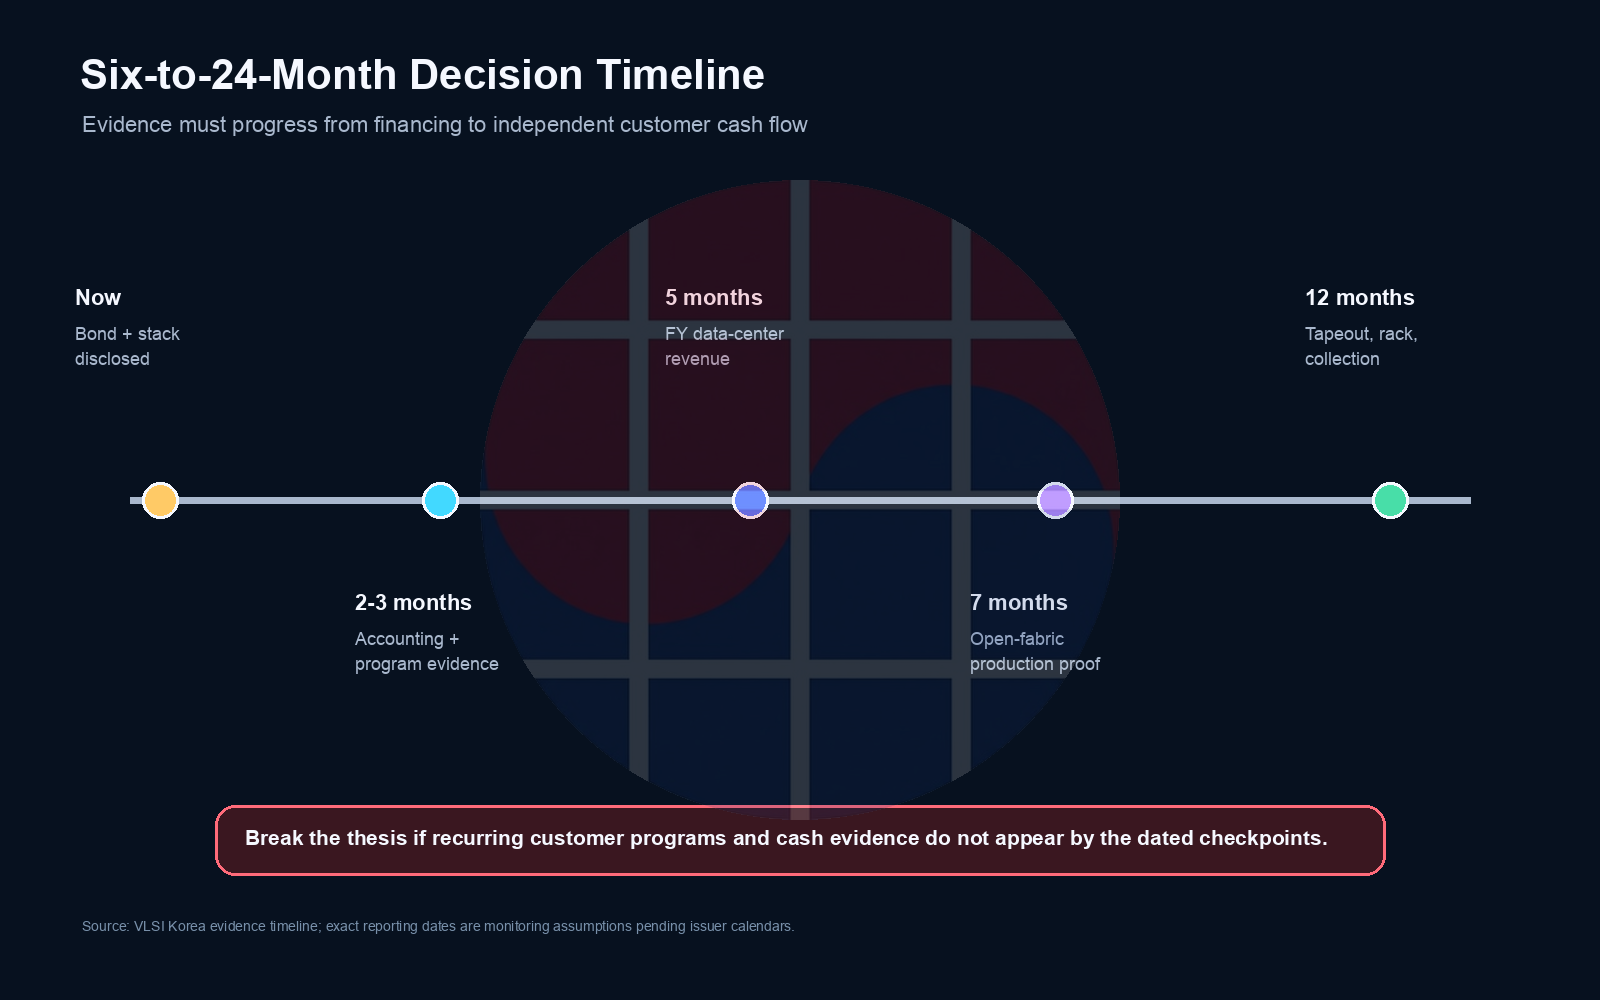
Final judgment: 현재 가장 defensible한 interpretation은 completed custom-XPU win도, meaningless financial loop도 아니다. Customer architecture에서 qualified rack까지 가장 짧은 path를 NVIDIA interface로 만들려는 financed attempt다. Repeatable and independently funded cash가 생길 때만 thesis가 강해진다.
Decision checklist는 열 가지다. 첫째, definitive bond terms가 filed됐는가. 둘째, use of proceeds가 identifiable program에 연결되는가. 셋째, customer와 workload가 named됐는가. 넷째, tapeout 또는 production milestone이 발생했는가. 다섯째, package, HBM, fabric qualification이 공개됐는가. 여섯째, connected mix를 측정할 수 있는가. 일곱째, segment margin을 보거나 합리적으로 bound할 수 있는가. 여덟째, inventory와 cash conversion이 ramp와 일치하는가. 아홉째, open standard가 comparable production qualification을 보이는가. 열째, repeat order와 collection이 partner financing이 아니라 customer에게서 오는가.
결론은 dramatic하기보다 disciplined해야 한다. NVIDIA의 US$3.5 billion MediaTek convertible은 custom-XPU economics를 compute die 하나에서 qualified attachment stack으로 이동시킬 수 있다. Public evidence는 mechanism과 monitoring plan을 정의하기에 충분하다. Realized unit volume, attachment revenue, segment margin, free cash flow, shareholder return을 주장하기에는 부족하다. 앞으로 6-24개월이 제공해야 할 fact가 바로 이것이다.
Sources and method
- NVIDIA, joint partnership and convertible announcement, 2026-08-31.
- MediaTek, joint partnership and convertible announcement, 2026-08-31.
- NVIDIA Form 10-Q, quarter ended 2026-07-26.
- MediaTek financial information, monthly revenue through July 2026.
- MediaTek Q1 2026 earnings release.
- NVIDIA NVLink Fusion ecosystem release, 2025-05-18.
- NVIDIA NVHBM technical overview, 2026-08-26.
- MediaTek data-center and rack-integration disclosure, 2026-05-28.
- MediaTek DGX Spark and GB10 co-design release, 2025-10-14.
- MediaTek AI data-center solution and 2026 revenue-guide blog, 2026.
- MediaTek corporate update, later blog와 publication-date context를 분리.
- Marvell NVLink Fusion partnership release, 2026-03-31.
- UALink Consortium, UALink 2.0 release, 2026-04-07.
- UCIe Consortium, UCIe 3.0 release, 2025-08-05.
- PCI-SIG, PCI Express 7.0 specification page, 2025-06-11.
- Reuters transaction cross-check, 2026-08-31.
- Bloomberg transaction cross-check, 2026-08-31.
- TechCrunch strategy cross-check, 2026-08-31.
- Dow Jones Newswires transaction cross-check, 2026-08-31.
AI assistance note: AI tool은 public-source discovery, arithmetic verification, bilingual consistency check, visual drafting, copy editing을 지원했다. Thesis, source interpretation, uncertainty label, publication decision의 책임은 VLSI Korea editorial review에 있다. Scenario output은 transparent sensitivity이며 company forecast가 아니다.
본 글은 정보 제공만을 목적으로 하며, 특정 증권의 매수 또는 매도를 권유하는 것이 아닙니다. 본 글에 포함된 수치와 사실은 기업 공시, 언론 보도, 시장 조사 등 공개적으로 이용 가능한 자료를 바탕으로 작성되었으며, 해당 자료 또는 작성 과정에서 오류가 발생할 수 있습니다. 필자는 언급된 기업의 주식을 보유하고 있을 수 있습니다. 모든 투자 결정 및 그에 따른 결과는 독자의 책임입니다.
관련 글