VLSI Korea
Cambricon Q3 Earnings: 8 Facts — Profit Up 148%, Growth Locked in a RMB 14.7B Stockpile (Cambricon, China AI Chips)
Cambricon posted record Q3 revenue of RMB 3.531B (up 104.5%) and net profit of RMB 1.404B (up 147.7%), yet revenue missed the market expectation by over 40% and RMB 14.7B sits in inventory and prepayments. Deliveries, not demand, set the ceiling — here are the 8 facts.


🆓 Free article · Anyone can read this article for free
Start with the conclusion. Cambricon Technologies (Shanghai: 688256), China's leading listed AI chip designer, reported third-quarter results on the evening of October 23, 2026: revenue of RMB 3.531 billion, up 104.5% year over year, and net profit of RMB 1.404 billion, up 147.7% — both quarterly records. The underside matters more. Revenue landed more than 40% below the roughly RMB 6.26 billion market expectation reported by Bloomberg, and RMB 14.7 billion of inventory and prepayments is tied up in the supply chain. This was a quarter where deliveries, not demand, set the ceiling. Here are the 8 facts, with the follow-up analysis published on October 24.
Figures are from the company's Q3 2026 report (filed October 23, 2026), cross-checked across multiple outlets. Market expectations and analyst comment are from Bloomberg and SCMP reporting (October 23-24); share price and market value are as of the October 23 Shanghai close.
Key numbers at a glance
| Item | Q3 (Jul-Sep) result | Year over year |
|---|---|---|
| Revenue | RMB 3.531B | +104.5% (quarterly record) |
| Net profit | RMB 1.404B | +147.7% |
| Net profit excl. non-recurring items | RMB 1.358B | +168.1% |
| Nine-month revenue / net profit | RMB 9.526B / RMB 3.715B | +106.8% / +131.5% |
| Nine-month gross margin | ~56.5% | +1.2 points |
| Inventory (Sep 30) | RMB 11.665B | +136% vs end-2025 |
| Prepayments (Sep 30) | RMB 3.044B | +309% vs end-2025 |
| Share price (Oct 23 close) | RMB 932.20 | +5.46% (closed before the release) |
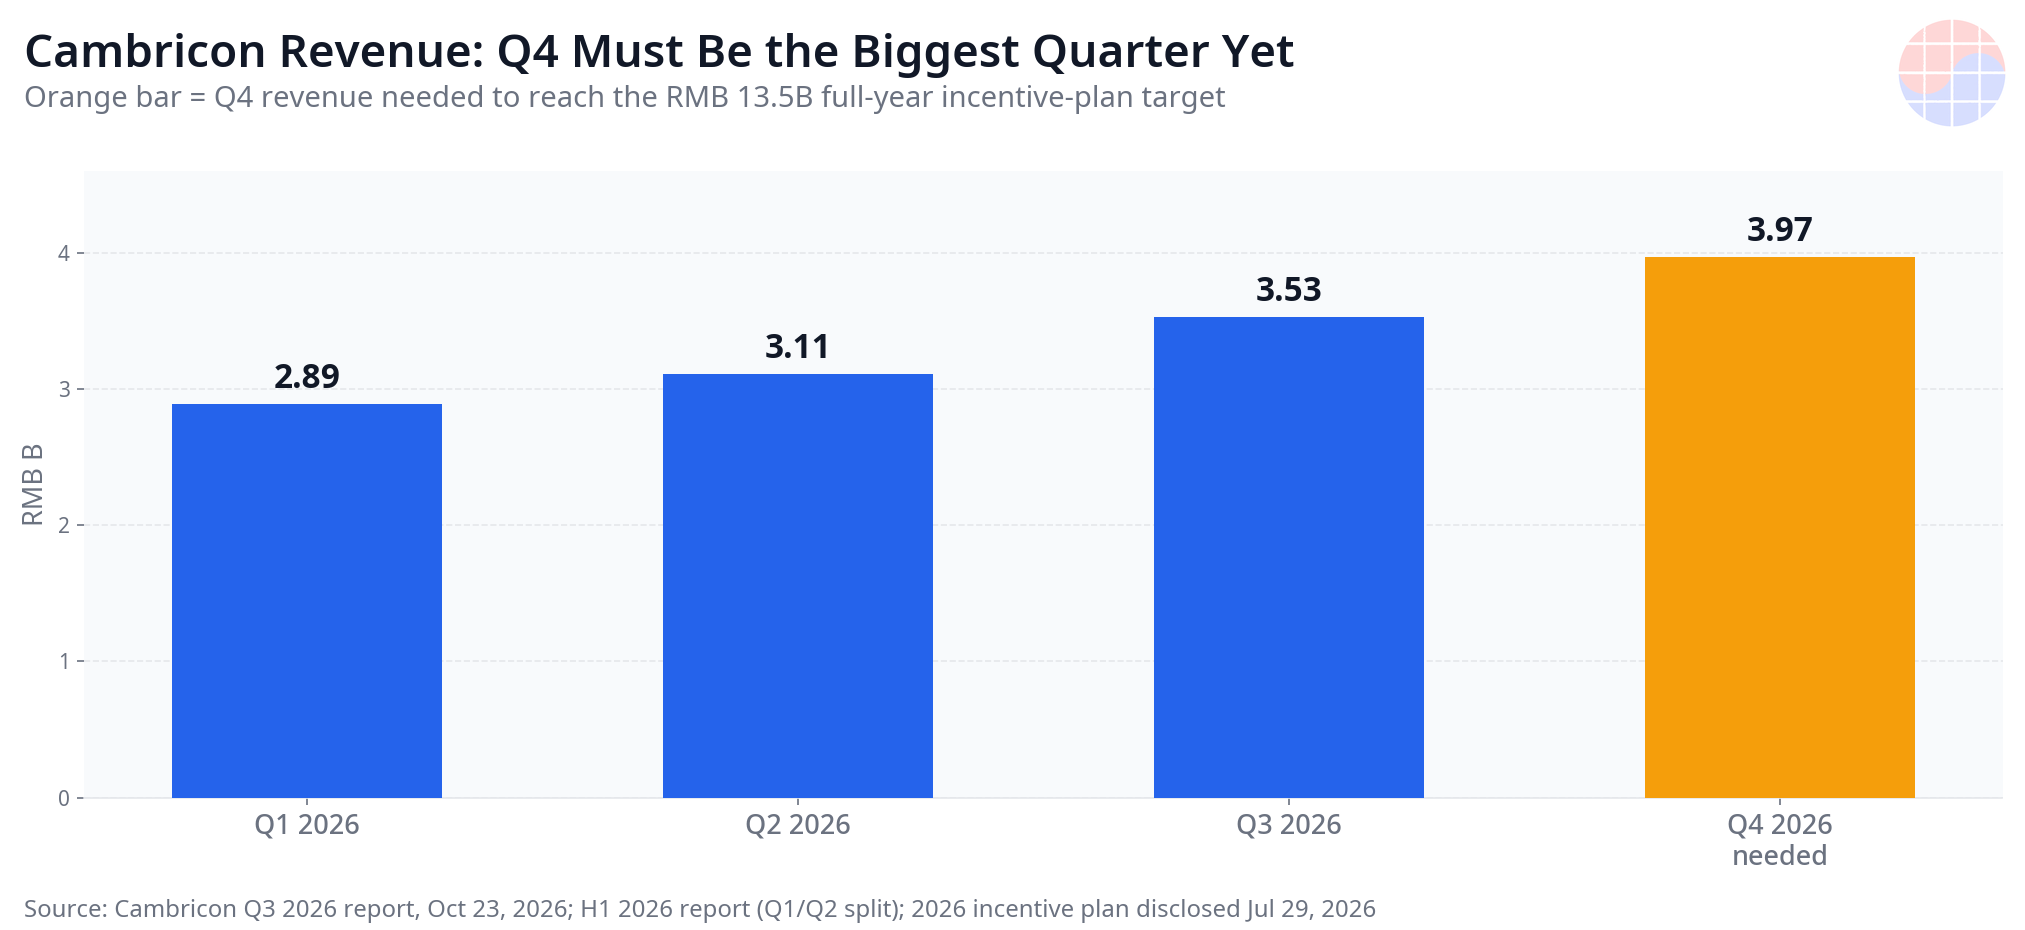
Quarterly revenue climbed in steps: RMB 2.89B in Q1, RMB 3.11B in Q2, RMB 3.53B in Q3. The RMB 13.5B full-year target requires roughly RMB 3.97B in Q4. Source: Cambricon Q3 2026 report, H1 2026 report, 2026 equity incentive plan.
8 facts
1. Revenue doubled — and the growth rate accelerated
Q3 revenue of RMB 3.531 billion, up 104.5% year over year, is a quarterly record, and the growth rate picked up from Q2's 75.8%. The company attributed the increase to continued market expansion and work to put AI applications into production, adding that higher revenue directly drove the profit growth.
2. Profit grew faster than revenue
Net profit rose 147.7% to RMB 1.404 billion, and profit excluding non-recurring items rose 168.1% to RMB 1.358 billion. Basic earnings per share were RMB 2.23. Nine-month net profit of RMB 3.715 billion already exceeds full-year 2025 net profit (RMB 2.059 billion) by 80%. Profit quality did not deteriorate: the cleaned-up profit line grew faster than the headline line.
3. The margin says this growth was not bought with price cuts
Nine-month gross margin was about 56.5%, up 1.2 points year over year. Selling, administrative and financial expenses together were just 2.1% of revenue, and R&D of RMB 1.225 billion (up 45.4%) fell to 12.9% of revenue. This is textbook operating leverage: scale is diluting a relatively fixed cost base.
4. And yet revenue missed the market expectation by more than 40%
The market expectation reported by Bloomberg was about RMB 6.26 billion; actual revenue came in at little more than half of that. The shortfall was not demand. Follow-up analysis converged on the same point: wafer output and HBM availability limited how much the company could deliver. Shares rose 5.46% into the October 23 close, but the results came after the close — the Shanghai market's verdict lands on Monday.
5. RMB 14.7 billion is tied up in inventory and prepayments
Inventory reached RMB 11.665 billion at September 30, up 136% from RMB 4.944 billion at the end of 2025; prepayments quadrupled to RMB 3.044 billion. The combined RMB 14.709 billion is, by one analysis, roughly two-thirds of total assets. For a fabless company, stockpiling at this scale is what it takes to secure wafers and HBM: without paying first, there is nothing to deliver.
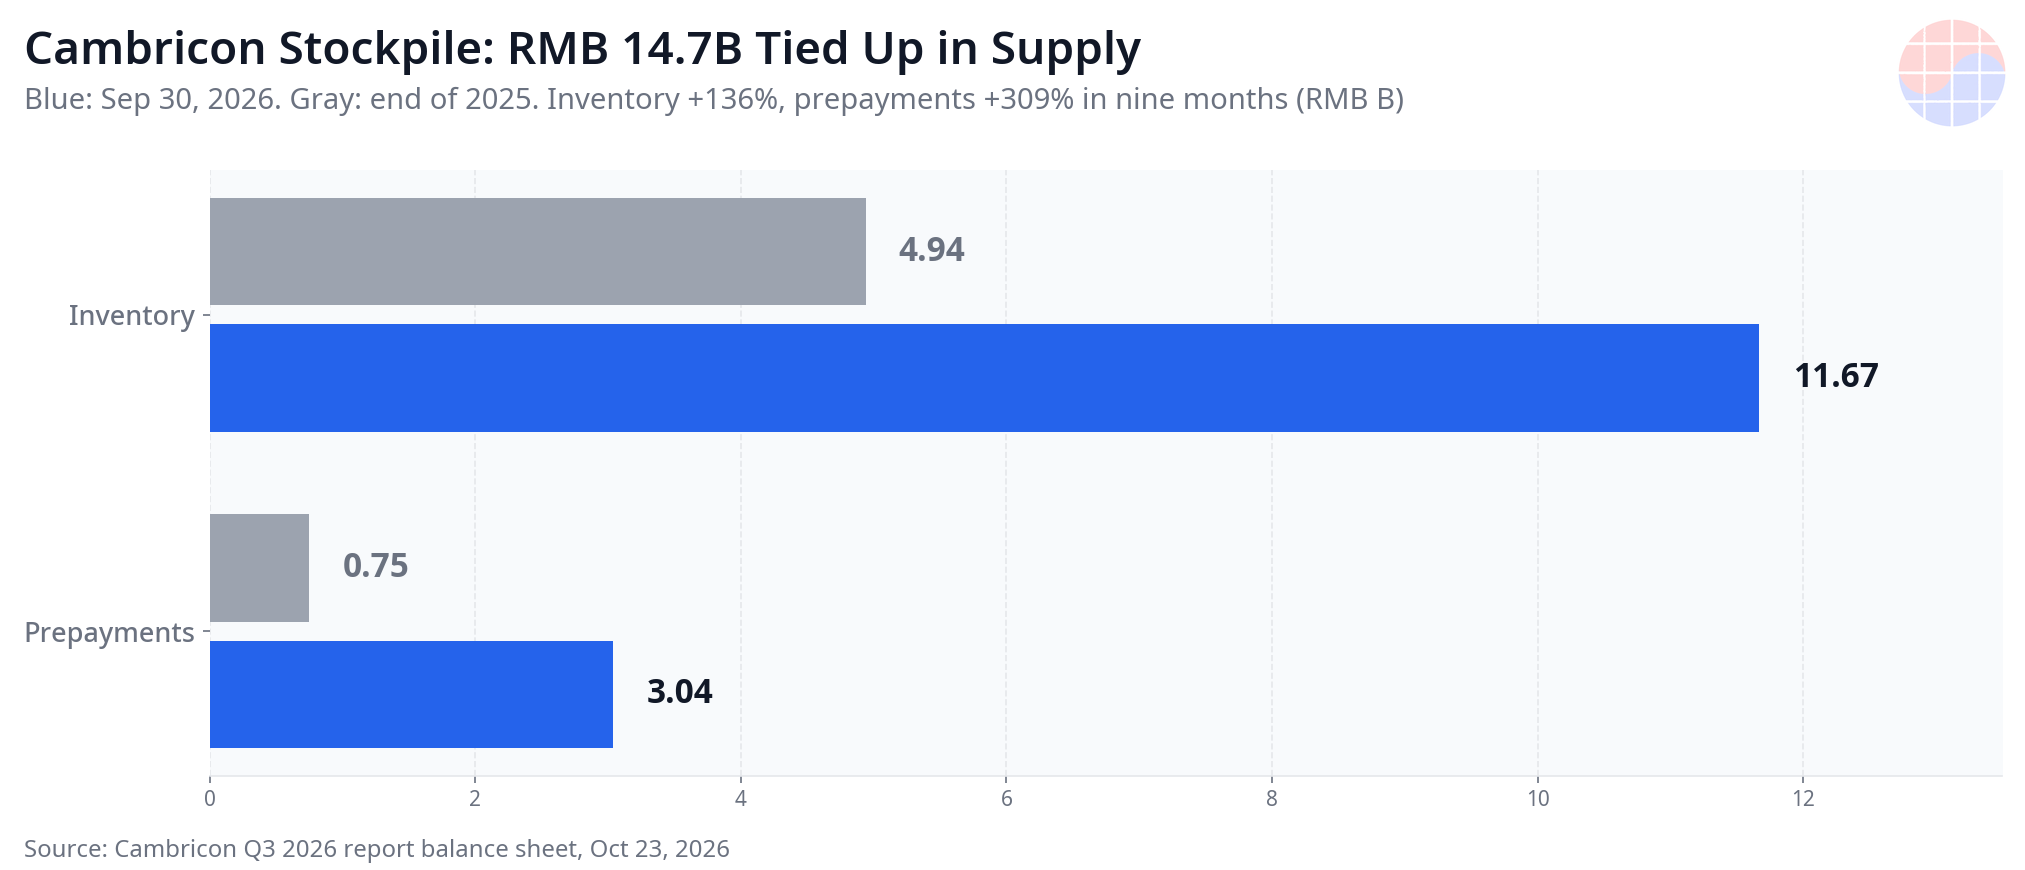
Inventory plus prepayments rose from RMB 5.69 billion to RMB 14.71 billion in nine months. Source: Cambricon Q3 2026 report, balance sheet.
📩 Following this story?
Get the follow-up analysis — earnings, reports and HBM supply — in your inbox daily at 10:30 KST. Subscribe free →
6. Profit and cash are moving on different clocks
Nine-month operating cash flow was just RMB 228 million, and Q3 alone was a net outflow of RMB 83.7 million. Cash received from sales reached RMB 10.671 billion, but cash paid for goods and services was RMB 8.99 billion. Asset impairment provisions hit RMB 502 million in nine months, nearly six times the RMB 87 million a year earlier, and in Q3 receivables rose RMB 720 million while revenue rose RMB 420 million sequentially. Profit is being booked; cash is being spent first on stockpiles and receivables.
7. Morgan Stanley is watching Q4 — and the binding constraint is HBM
Morgan Stanley wrote that the MLU692, the company's newest chip, was delivered to a major cloud service provider in Q3 for testing, but that most revenue recognition will come in Q4. MLU580 shipments, by contrast, remain limited because higher HBM costs pressure unit economics. An earlier Morgan Stanley report credited the MLU690 series with outperforming Nvidia's H20 by 50 to 150% on tokens per second. The diagnosis is not product competitiveness — it is HBM cost and allocation.
8. The Q4 test: one more record quarter is required
The first gate in the equity incentive plan disclosed on July 29, 2026 is full-year revenue of at least RMB 13.5 billion. Nine months delivered RMB 9.526 billion (70.6% of the gate), so Q4 needs about RMB 3.974 billion — 12.5% above the record Q3. The later gates are steeper still: the ladder implies RMB 27 billion in 2027 alone and RMB 59.5 billion in 2028 alone. In a same-day statement, the company said AI compute demand remains strong, gross margin is high and stable, and growth should continue. Market value, at RMB 586.2 billion, is down more than 40% from the trillion-yuan peak three months earlier. The market is already repricing the company on delivery capacity.
The peer comparison — Hygon printed in the same week
Hygon, the other pillar of China's domestic AI chip sector, posted Q3 revenue of RMB 5.9 billion (up 45.5%) and net profit of RMB 1.0 billion (up 37.9%) in the same week. Hygon is larger on revenue; Cambricon is growing faster. Both are filling the space left by US export controls on Nvidia, and both are capped by supply rather than demand.
Chase's Take
My rule for this kind of print: read the balance sheet before the income statement. RMB 14.7 billion of inventory and prepayments is the real guidance. Management has put cash, not words, into wafers and HBM, and Q4 revenue is now a function of how fast that stockpile passes customer acceptance and converts into recognized sales.
For Korean readers, the connective tissue is HBM. If HBM prices are what squeeze MLU580 unit economics, the beneficiaries of that price strength report next week: SK hynix on October 28 and Samsung Electronics on October 29. Chinese accelerator makers queue behind Nvidia and AMD for HBM allocation, and the only path that changes that structure is qualified domestic HBM production. Cambricon's stockpiling race is also evidence that Korean memory pricing power extends into China.
Profit quality is genuinely improving. The open question is cash conversion. A model where profit is booked while cash leaves first for inventory only holds if Q4 acceptance goes smoothly. Miss the RMB 4 billion mark in Q4 and the whole incentive ladder (RMB 27 billion in 2027, RMB 59.5 billion in 2028) wobbles — and the impairment line, already above RMB 500 million, shows how two-edged the stockpile is. Clear it, and the company has proven it can buy supply with money and turn it into revenue on schedule.
What to watch next
- Monday, October 27 in Shanghai: the first session after the release — how the market digests the expectation miss.
- SK hynix on October 28 and Samsung Electronics on October 29: whether HBM price and volume commentary points the same way as Chinese accelerator makers' cost pressure.
- Q4 revenue recognition: whether MLU692 revenue lands in Q4 as Morgan Stanley expects, and whether the RMB 13.5 billion full-year gate is cleared.
- Inventory composition: raw materials versus outsourced processing in the annual report, and the impairment trend.
Related: Western Digital earnings in 8 facts — the guidance that beat the beat · DISCO earnings — record sales, a stock at its year low · BofA on memory valuations — the price frame before SK hynix and Samsung report
FAQ
What were Cambricon's Q3 2026 results?
Revenue of RMB 3.531 billion (up 104.5% year over year), net profit of RMB 1.404 billion (up 147.7%), and net profit excluding non-recurring items of RMB 1.358 billion (up 168.1%) — all quarterly records. Nine-month revenue was RMB 9.526 billion (up 106.8%) and net profit RMB 3.715 billion (up 131.5%).
Why did revenue miss expectations despite doubling?
The market expectation reported by Bloomberg was about RMB 6.26 billion, more than 40% above the actual figure. Analysts attribute the gap to supply — wafer output and HBM availability limiting deliveries — not to demand. Morgan Stanley also noted that MLU580 shipments remain limited by HBM cost pressure.
Why is inventory so large, at RMB 11.665 billion?
Cambricon is fabless: wafer fabrication and packaging are outsourced, so securing volume means paying in advance through inventory and prepayments. The two combined rose from RMB 5.69 billion to RMB 14.71 billion in nine months. Whether that stockpile converts into Q4 revenue is the central question.
What has to happen in Q4?
To clear the RMB 13.5 billion full-year revenue gate in its equity incentive plan, Cambricon needs about RMB 3.974 billion of Q4 revenue, 12.5% above the record Q3. The swing factors are MLU692 revenue recognition, which Morgan Stanley expects to concentrate in Q4, and the speed at which inventory converts into accepted deliveries.
Sources
Cambricon Q3 2026 report and operating update (filed October 23, 2026, Shanghai Stock Exchange), cross-checked across multiple outlets. Market expectation and supply-constraint analysis from Bloomberg reporting (October 23, 2026); Morgan Stanley comment and Hygon results from SCMP (October 24, 2026); incentive targets from the company's 2026 restricted stock incentive plan draft (disclosed July 29, 2026). This article is for information only and is not investment advice.
📩 Missed today's analysis? Get tomorrow's in your inbox
Daily Silicon at 10:30 KST plus earnings and analyst-report breakdowns, first. Samsung Electronics, SK hynix, TSMC and HBM supply, read by practicing engineers. Join 300+ subscribers.
Subscribe free →
Free · No spam · Unsubscribe anytime