VLSI Korea
Akamai–Anthropic CPU Deal and Nscale Financing | Daily Silicon
Eleven semiconductor and AI infrastructure developments: Akamai, Nscale, Solidigm, CanSemi pricing, TSMC design tools and optical links.


🆓 Free article · Anyone can read this article for free
Executive Summary
- Akamai’s $11.6bn Anthropic CPU deal brings memory purchases forward
- Nscale’s $3.36bn financing includes a later NVIDIA tranche
- Oracle’s Jupiter power concerns reach the financing contract
- Solidigm IPO report floats a valuation, not a completed transaction
- CanSemi prices its IPO at CNY12.01, implying CNY6.16bn before fees
- Cadence’s TSMC A14 certification spans different IP readiness stages
- Tower details its Japan optical-chip hub within an existing $4bn plan
- Perplexity local workflows reach AMD PCs, with cloud use still a separate choice
- PicoJool’s $27.5m Series A funds the path toward optical-link qualification
- DOE selects 31 grid projects for intended SPARK support
- VIRTUS secures £2.45bn of financing commitments for expansion
01 Akamai’s $11.6bn Anthropic CPU deal brings memory purchases forward
TL;DR Akamai announced a seven-year, $11.6bn commitment for Anthropic’s CPU workloads. It expects about $1.7bn of additional capital spending this year to secure components including memory.
Catch-up on the September 24 announcement or report, not a new announcement today.
The service supports CPU workloads, rather than a GPU training cluster. Akamai estimates related total capex at roughly $5.5bn. A possible additional $9bn expansion is conditional and should not be counted as committed business.
For semiconductor suppliers, the notable sequence is component procurement before service revenue. Akamai says the agreement does not change its current-year revenue outlook. The next question is how quickly those advance purchases become operating capacity and cash receipts.
Sources · Akamai (2026-09-24)
02 Nscale’s $3.36bn financing includes a later NVIDIA tranche
TL;DR Nscale announced $3.36bn of convertible financing ahead of its proposed IPO. The initial closing is $2.36bn; NVIDIA’s separate $1bn commitment is expected to fund in mid-November.
Catch-up on the September 25 announcement or report, not a new announcement today.
The notes automatically convert into shares when the IPO completes, with NVIDIA receiving non-voting shares. The headline total therefore differs from cash already received or proceeds from a public share sale.
This is a financing milestone separate from the previously reported listing application. Infrastructure spending continues while a company prepares to float. The subsequent funding and the IPO are distinct checkpoints for assessing how much capital can support construction and equipment purchases.
Sources · Nscale (2026-09-25)
03 Oracle’s Jupiter power concerns reach the financing contract
TL;DR Reuters cited an unnamed source saying Oracle sent a force-majeure notice to Project Jupiter’s developer. Oracle maintained its schedule, while Blue Owl said the project’s financial commitments were unchanged.
Catch-up on the September 24 announcement or report, not a new announcement today.
The September 25 follow-up still presented conflicting schedule accounts. MT Newswires relayed a Reuters source’s report of a one-year delay and added Oracle’s emailed response maintaining its schedule. The notice alone does not establish cancellation or a final legal release from obligations.
For chip demand, the case illustrates why a data-center contract value cannot establish a server commissioning date. Power and facility readiness can change the interval between equipment delivery, acceptance and service activation. Subsequent schedule disclosures and cost allocation remain the relevant checks.
Sources · Reuters via MarketScreener · MT Newswires: September 25 update and Oracle response (2026-09-24)
04 Solidigm IPO report floats a valuation, not a completed transaction
TL;DR Reuters sources said Solidigm was considering an IPO as early as 2027. The report discussed a valuation up to $150bn and a potential $15bn raise; SK hynix said specific plans were unconfirmed.
Catch-up on the September 25 announcement or report, not a new announcement today.
This is not an approved offering or an established offer price. The reported valuation, proceeds and timing may change. It is also a separate event from earlier reporting about a possible US NAND factory.
An external capital raise would warrant examining investment funding alongside the parent’s ownership. That is the industrial question raised by the report. It does not yet provide a basis for calculating additional manufacturing capacity or NAND supply; an actual filing would be the next evidence point.
Sources · Reuters via StreetInsider (2026-09-25)
05 CanSemi prices its IPO at CNY12.01, implying CNY6.16bn before fees
TL;DR CanSemi set its IPO price at CNY12.01 per share and scheduled subscriptions for September 24. Multiplying that price by 512.646 million base shares gives approximately CNY6.16bn of gross proceeds.
Catch-up on the September 22 announcement or report, not a new announcement today.
Pricing is a new milestone beyond the earlier funding-target story. This calculation excludes the over-allotment option and offering fees. It does not establish completed payment or the start of trading; the notice also identifies continuing losses.
The industrial checkpoint is when the offering becomes usable funding for equipment and technology development. Finalized offer terms alone do not guarantee more capacity or improved profitability. Allocation, payment and subsequent use-of-proceeds disclosures remain separate steps.
Sources · CanSemi issuance notice via China Securities Journal (2026-09-23)
06 Cadence’s TSMC A14 certification spans different IP readiness stages
TL;DR Cadence announced A14 tool certification and silicon-proven UALink IP on TSMC N3P. The announcement broadens design readiness, but its individual IP blocks are at different stages.
Catch-up on the September 23 announcement or report, not a new announcement today.
Certification, tape-out and ongoing development appear together in the release. Some A14 foundation IP is expected in the fourth quarter. Treating tool certification as completed production validation for every block would distort a project schedule.
A design team needs to check the chosen block, tool version, validation scope and availability date together. The useful change is a wider set of options for starting designs. It does not guarantee the yield or delivery date of a particular customer chip.
Sources · Cadence (2026-09-23)
07 Tower details its Japan optical-chip hub within an existing $4bn plan
TL;DR DCD reported that Tower’s CEO outlined Japan’s role as its largest optical-chip hub in a Nikkei interview. The details concern a $4bn investment plan announced in July, rather than another $4bn on top.
Catch-up on the September 24 announcement or report, not a new announcement today.
The report describes an Arai conversion and Uozu expansion, with $1bn of Japanese government support included in the total. Its 2029 target is 45,000 monthly wafers on a 300mm-equivalent basis, not current shipments.
Turning optical demand into revenue requires packaging and customer qualification as well as wafer manufacturing. Construction progress and product-specific approvals therefore matter. The interview clarifies the execution path without establishing that the target capacity is already available.
Sources · Data Center Dynamics, citing Nikkei (2026-09-24)
08 Perplexity local workflows reach AMD PCs, with cloud use still a separate choice
TL;DR Perplexity subscribers can now use Portable Computer on supported Ryzen AI Max Windows PCs. AMD says inference for local tasks does not consume Perplexity Computer credits.
Catch-up on the September 24 announcement or report, not a new announcement today.
The supported platforms include Ryzen AI Halo. The announcement combines local execution with optional cloud use. It does not mean subscriptions are free or that every task and all its data must remain on the PC.
A purchasing decision should begin with whether the intended workflow suits the local model, then examine data permissions and cloud handoffs. This adds a software route for using the hardware. It is not a benchmark establishing a speed advantage for every workload.
Sources · AMD (2026-09-24)
09 PicoJool’s $27.5m Series A funds the path toward optical-link qualification
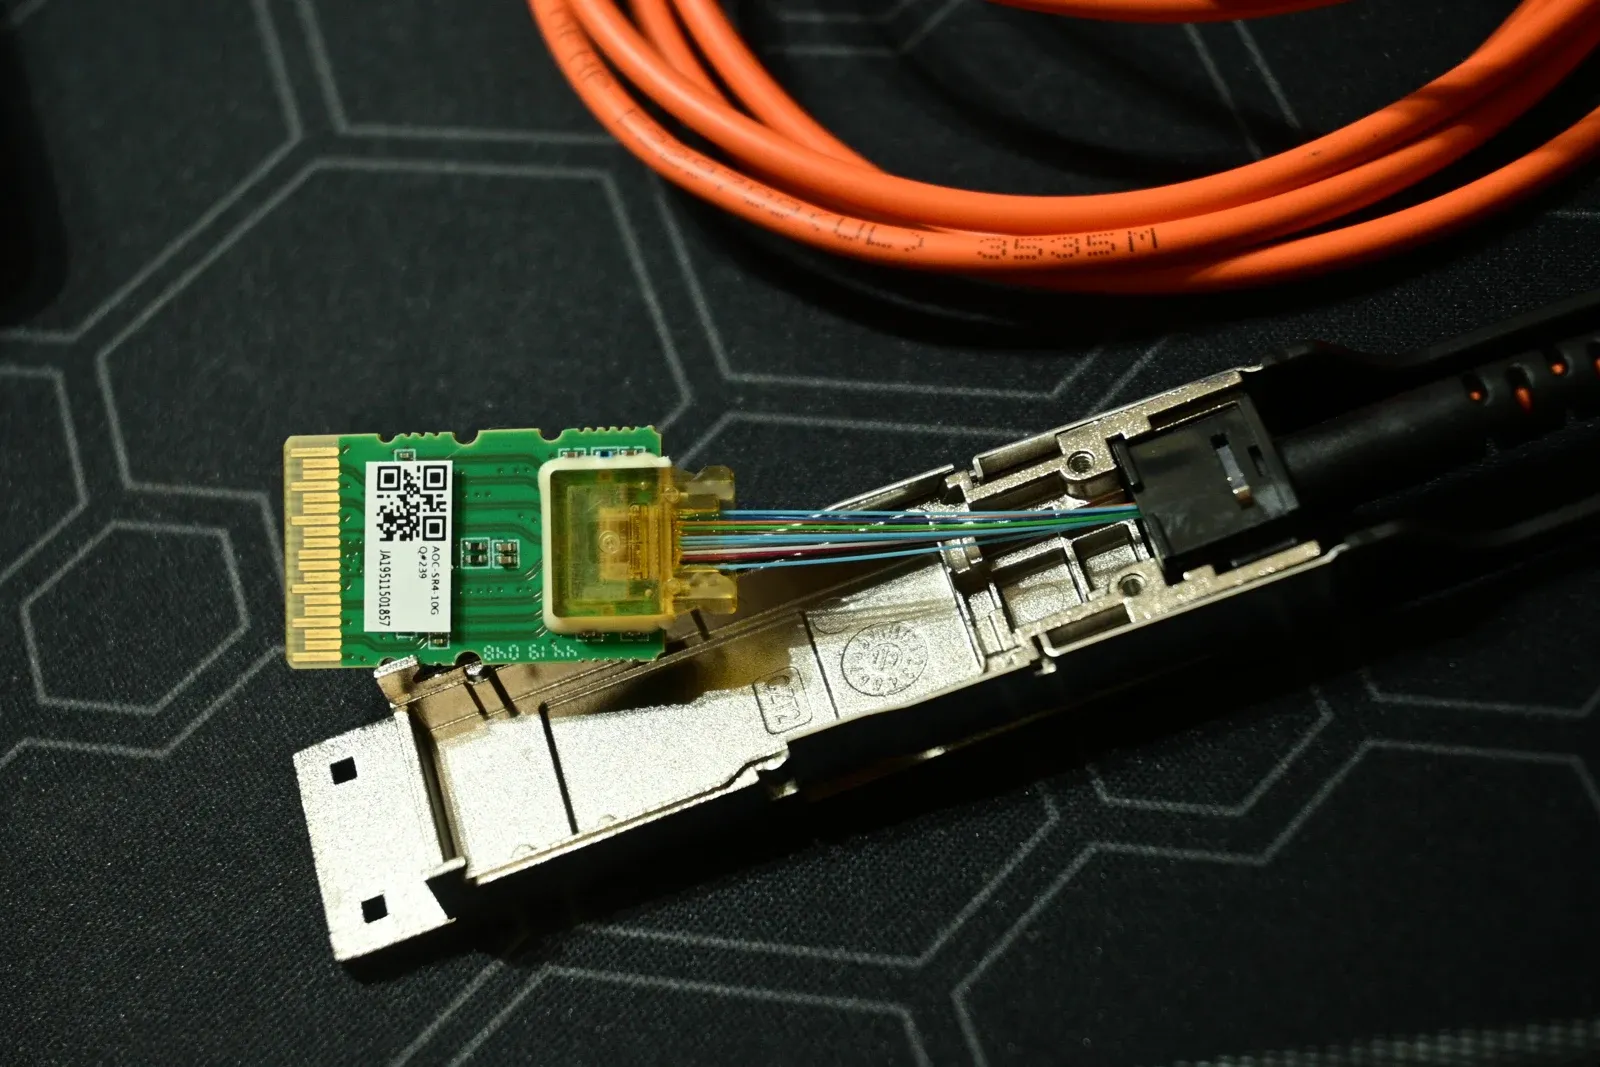
TL;DR PicoJool announced a $27.5m Series A round. It plans to expand US and Taiwan operations and prepare VCSEL optical-link products for qualification and manufacturing.
Catch-up on the September 24 announcement or report, not a new announcement today.
Including its earlier seed round, cumulative funding is $39.5m. The company says early chip-level VCSEL sampling has begun. Round size differs from lifetime funding, just as sampling differs from volume production.
Optical components still need customer-system validation and reliable manufacturing after a performance demonstration. The financing supports that execution gap. The announcement alone cannot establish adoption volumes or when development will translate into revenue.
Sources · PicoJool (2026-09-24)
10 DOE selects 31 grid projects for intended SPARK support
TL;DR The US Energy Department announced plans to support 31 grid projects across 26 states. The planned $5.25bn total combines $1.9bn of federal funding with $3.35bn of recipient cost sharing.
Catch-up on the September 24 announcement or report, not a new announcement today.
SPARK emphasizes replacing transmission conductors and improving existing-grid performance. The announcement concerns intended support and expected benefits, rather than completed construction or full disbursement. It is not an exclusively AI-data-center program.
Fabs and data centers need electricity delivered to their locations, not simply more generation elsewhere. Using existing transmission infrastructure addresses a different bottleneck from developing new sites. Project completion and usable connection capacity remain the practical follow-up measures.
Sources · US Department of Energy (2026-09-24)
11 VIRTUS secures £2.45bn of financing commitments for expansion
TL;DR VIRTUS announced a £2.45bn financing package. It includes a £1.2bn green capex facility supporting expansion in the UK and Europe.
Catch-up on the September 24 announcement or report, not a new announcement today.
The company identifies its planned 78MW Saunderton campus among the developments supported. Committed financing is not construction spending already disbursed, and planned capacity is not currently energized IT load. Financing and completion are separate milestones.
Connecting the announcement to chip demand requires following construction, power delivery and customer equipment installation after funding draws. The deal reduces uncertainty about development finance. Server choices and commissioning dates still require their own contractual and operating evidence.
Sources · VIRTUS Data Centres (2026-09-24)
Silicon Market · 15
13 US listings use TradingView; two Korean listings use Naver links. Quotes are dynamic and may be delayed. Closing snapshots and ±3% mover research checks remain incomplete.
Allow external services in cookie settings to show the chart.
All 15 semiconductor stocks
Samsung Electronics · 005930 · Naver Finance
SK hynix · 000660 · Naver Finance
Related reading
- Global chip sales pass $1T; Broadcom–Anthropic $42B financing | Daily…
- TSMC Eyes Sixth Straight Record Profit; Intel, Qualcomm Hike CPU Prices…
- Nscale IPO, Crusoe Funding and Solidigm’s US NAND Fab Talks | Daily Silicon
- SK hynix–Intel Talks, Winbond Deal and MLPerf | Daily Silicon
- Fujitsu MONAKA CPU sales, Korea chip exports and AI infrastructure |…