VLSI Korea
Daily Silicon: NVIDIA D-day, Triple Memory PT Hike
TL;DR — NVIDIA reports Q1 FY27 after the May 20 close. Consensus revenue ~$78B (whisper $79-80B), non-GAAP EPS $1.77, data center revenue ~$73B. Options are...


🆓 무료 글 · 누구나 무료로 읽을 수 있는 글입니다
A practicing semiconductor engineer's daily read on global silicon news:
NVIDIA reports fiscal Q1 today with consensus at $78B revenue / $73B DC and options pricing ±8-10% moves, while Mizuho lifted Micron ($800), TXN ($300), and STM ($68) targets simultaneously and Nomura sees another 110% upside in Korean memory names.
Chase's Take — From an STA/backend engineer's seat, today's most important signal isn't NVIDIA's revenue print — it's Hanmi Semiconductor's 30% collapse. TC bonder revenue dropping 65.5% QoQ means HBM3E line capex has run its course and HBM4 16-Hi bonders aren't booked yet, reconfirming that memory ramp isn't a smooth multiplicative curve but a staircase with generational discontinuities. Mizuho taking Micron's PT to $800 while explicitly stating 'supply tight through 1H 2027' means HBM4 cube quality yield and TSV stack yield — i.e., back-end — are dragging the ASP curve, which lines up with Lam Research guiding advanced packaging revenue +50%. If the union strike actually kicks off on the 21st, JPMorgan's 2.1-3.5 trillion won OP hit lands directly on the quarterly P&L, but the real problem is the second-order effect: Pyeongtaek P3 HBM4 line qual slips, and the H2 2026 ramp tilts further toward SK hynix/Micron. Next quarter's watch-points: (1) whether H200 China revenue gets visibility on tonight's NVIDIA call, (2) whether the May 21 strike actually takes effect, (3) whether TSMC's May revenue on June 10 prints another -1.1% MoM after April. The memory cycle isn't peaking now — the peak is when HBM4E qual finishes in 1H 2027, and the PT-raise race trying to front-run it just started with Mizuho's triple. That's why former president Kyung Kye-ho's 'H2 2027 price decline' warning carries weight.
1. NVIDIA Q1 FY27 earnings preview — consensus $78B / DC $73B / non-GAAP EPS $1.77, Blackwell→Rubin handoff is the key
TL;DR — NVIDIA reports Q1 FY27 after the May 20 close. Consensus revenue ~$78B (whisper $79-80B), non-GAAP EPS $1.77, data center revenue ~$73B. Options are pricing an 8-10% move, and with Blackwell at close to 70% of data center compute last quarter, smoothness of the Rubin handoff and China commentary are the call's biggest variables.
2. Samsung labor-management talks reach brink — bonus formula standoff, 18-day strike D-1

TL;DR — Samsung's union and management held last-mile talks May 19 over the bonus formula. Union demands a 15% semiconductor OP bonus pool split 70/30 (division-flat / business-unit performance); management counters 60/40 with a +9-10% bump if OP clears 200 trillion won. An 18-day strike by union members starts May 21 absent a deal.
3. SK hynix accelerates Yongin fab buildout — memory crunch fuels capacity race, schedule pulled 3 months
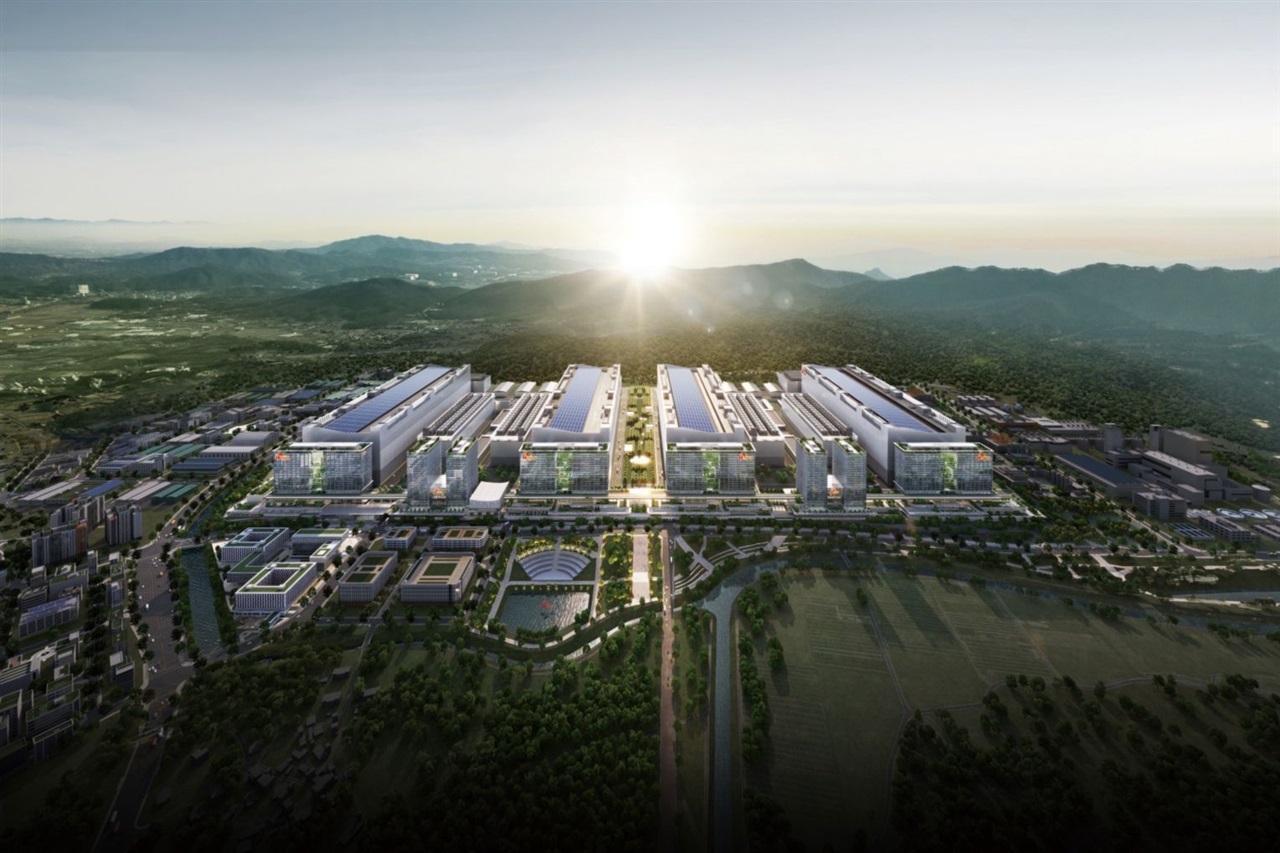
TL;DR — DIGITIMES (May 18): SK hynix is pulling Yongin Semiconductor Cluster construction forward — first fab ops 3 months ahead, second cleanroom opening ahead of schedule. AI-driven memory demand keeps the supply gap open past 2028, and hyperscaler cloud capex breaking $725B is the direct driver of the capex pull-in.
4. Hanmi Semiconductor crashes 30% in two days — Q1 earnings shock, HBM3E↔HBM4 transition air pocket

TL;DR — Hanmi Semiconductor dropped -16.73% on May 15 and -13.82% on May 18, vaporizing 8 trillion won in market cap (38T → 30T) in a week. 1Q26 OP came in at 84.56 billion won (-87.9% YoY) on revenue of 509 billion won (-65.5%), well short of consensus (revenue 1,900-2,000B / OP 900-1,000B). The cause: HBM3E TC bonder capex has wrapped and HBM4 bonder revenue hasn't ramped — a clean transition air pocket.
5. These chip stocks could extend historic gains by rallying over 110%, according to Nomura — Samsung·SK hynix bull thesis

TL;DR — CNBC (May 19): Nomura pegs Korean memory suppliers' revenue and earnings growth at ~30% annually over the next 3-5 years, with 2026 earnings rising seven- to eightfold. Nomura: 'memory vendors have entered an unprecedented phase of rapid revenue growth and margin expansion in a short period of time.' Bull thesis on Samsung and SK hynix in the AI memory cycle.
Frequently Asked Questions
What was the consensus for NVIDIA Q1 FY27?
Consensus was revenue of about $78 billion, data center revenue of about $73 billion, and non-GAAP EPS of $1.77. NVIDIA reported after the May 20 close, with options pricing an 8-10% move.
What price targets were raised for memory and analog names?
Mizuho lifted Micron to $800, Texas Instruments to $300, and STMicroelectronics to $68 at the same time. It stated memory supply stays tight through the first half of 2027.
Why did Hanmi Semiconductor fall 30% in two days?
Hanmi fell 16.73% on May 15 and 13.82% on May 18 after a Q1 earnings miss. HBM3E TC bonder capex has wrapped and HBM4 bonder revenue has not yet ramped.
How did SK hynix change its Yongin schedule?
SK hynix is pulling Yongin Semiconductor Cluster construction forward. First fab operations move 3 months ahead, and the second cleanroom opening also moves ahead of schedule.
Related reading
- Daily Silicon: NVIDIA Earnings Aftershock Reshapes ASIC and Materials…
- Daily Silicon: Only Nvidia Lags as Memory, Arm, and ASICs Power the…
- Daily Silicon: NVIDIA $81.6B, Q2 Guide $91B — Parabolic
- Daily Silicon: Analyst Consensus Surge vs TSMC April Slowdown,…
- Daily Silicon: AMD Helios: 72 GPUs, HBM4 and NVIDIA AI Chips